Pitch Deck Financials: What to Show and How to Tie It Out
Pitch deck financials: the five or six figures to show by company profile, how to draw history against forecast, and six checks that tie the slide to the model.

A pre-revenue company shows cost model and runway, a growing one revenue, growth and margin, an owner-led one EBITDA, cash conversion and net debt.
Actuals in one tone, the forecast in a second, the unit on the axis.
Every figure traces to one cell, ties to the accounts, uses one definition and moves with its assumption.
Cash today plus the raise, less net spend by use, equals cash at the milestone, with any debt on separate lines.
The SEC applies the federal antifraud provisions to exempt offerings too, so counsel reads the wording of the slide.
Pitch deck financials are the five or six figures an investor needs to size the business, drawn from the financial model and shown with their assumptions. The slide fails when a figure can't be traced to the model or the accounts.
The figures differ for a company with no revenue yet, a growing one and an owner-led business that already earns EBITDA.
| Step | Leads to |
|---|---|
| Accounts (Historical figures) | Financials slide [actuals] |
| Financial model (Forecast and every input) | Financials slide [forecast] |
| Financials slide (Five or six figures) | Investor asks where a figure comes from |
| Investor asks where a figure comes from | Data room [traced] |
| Data room (Full model and accounts) | end |
What does the pitch deck financials slide have to show?
Financials in a pitch deck answer three questions for the investor: how large the business is, how fast it's moving and whether the economics hold. Which figures answer them depends on what the company can prove today.
J.P. Morgan's guide to investor pitch decks says the finances to include depend on the stage of the company, with later-stage companies often showing predicted sales growth.
| Item | Years of revenue history (0 to 100) | Visibility of margin (0 to 100) | Note |
|---|---|---|---|
| Pre-revenue | 8 | 12 | Slide leads with the cost model, runway and milestones. |
| Revenue, growing | 50 | 52 | Slide leads with revenue, growth and gross margin. |
| Profitable, owner-led | 88 | 90 | Slide leads with EBITDA, cash conversion and net debt. |
A stage label is a rough guide. A 10-year-old company launching a new product line and a 2-year-old company with contracted revenue need different slides, so the table keys each profile to what it can prove.
3 columns. Drag the table sideways; the first column stays put.
Company profile | Figures on the slide | Stays in the model |
|---|---|---|
Pre-revenue | Monthly cost model, cash runway, cash needed for the milestone, the milestones the raise reaches, three assumptions behind the plan | Hiring plan by role, scenario runs, cost lines |
Revenue, growing | Revenue (ARR when it recurs), growth rate, gross margin, EBITDA or burn, one unit-economics pair | Cohort tables, pipeline by stage, cost detail |
Profitable, owner-led | Revenue, EBITDA, EBITDA margin, cash conversion, net debt | Monthly balance sheet, working-capital schedule, segment P&Ls |
Startup pitch deck financials have no history to chart before the first revenue, so the slide charts what the money buys: monthly cost, cumulative cash and the milestones placed on the cash line. The three assumptions behind the plan sit beside it with their basis, such as a price taken from a signed pilot or a conversion rate taken from a test.
For a growing company the unit-economics pair is usually customer acquisition cost with payback in months, or revenue per customer with churn. Pick the pair the business model is argued on, calculate both from the same customer data and show the same two on every version of the financials slide.
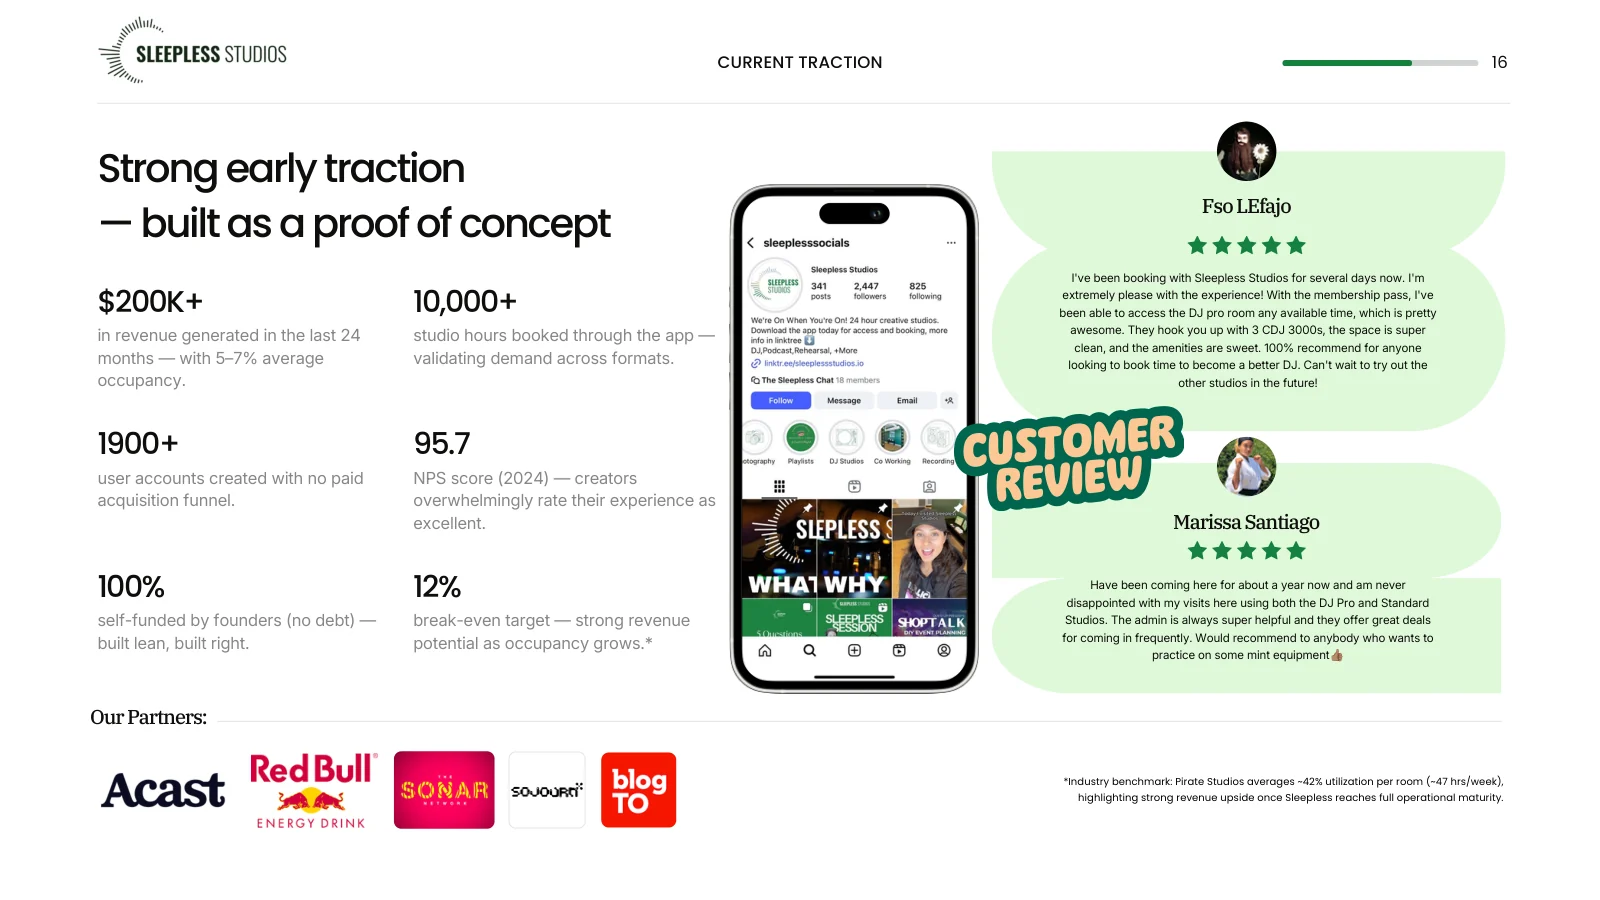
The traction slide above gives most of its figures a period or a basis: revenue over the last 24 months beside the average occupancy behind it, the NPS score with its year, and a break-even target with the industry benchmark in a footnote. The financials slides that follow it in the same deck aren't public; the test for them is the same, a period and a basis on every number.
A business with project or transaction revenue swaps ARR for revenue by year and the share already under contract. For the owner-led company, EBITDA (earnings before interest, tax, depreciation and amortisation) sits beside cash conversion, the share of EBITDA that turns into cash, because a profit that doesn't turn into cash doesn't repay debt.
In our pitch deck service, design comes last, after the argument and the research behind it are fixed, so a figure on this slide is settled before anyone draws it.
The customer count on the slide must equal the one on the traction slide.
How many years should pitch deck financial projections cover, and how do you draw them?
My default for pitch deck financial projections is three years of actuals and three forward years, cut on either side when the model can't carry it. The first forward year should equal the current budget, because it's the one year the company can defend line by line.
In filings, the SEC's policy on projections, set in Item 10(b) of Regulation S-K, is that management must have a reasonable basis for them. A private deck is outside that rule, though the antifraud provisions in the SEC paragraph further down still apply, so the test fits every forward figure on the slide.
Show one forecast, the base case. The upside and downside cases stay in the model, where each carries its own assumptions, and quarterly detail for the first forward year stays there too.
The pitch deck financials examples below, a slide and a table, use numbers that tie to each other, so the six checks later in this guide pass on them.
| Part | What it is |
|---|---|
| 1 | Revenue by year: actuals as solid bars, the forecast in a second tone |
| 2 | A visible break between actuals and forecast, and an A or F on each year |
| 3 | The driver beside the growth rate, in one line under the chart |
| 4 | A short table whose figures tie: revenue, gross margin and EBITDA for 2025 to 2027 |
| 5 | One unit everywhere: US dollars millions to one decimal, the same fiscal year end |
On the financial projection slide, draw actuals as solid bars and the forecast in a second tone, as the slide above does. Add a visible break between them and an A or F on each year. Label the axis in one unit, set the labels left-aligned and keep the chart to bars so the eye reads growth without a legend.
Under the chart goes a short table, and its figures are the ones that must tie. How much history fits grows with the company, as how a deck changes by stage shows.
4 columns. Drag the table sideways; the first column stays put.
Illustrative example, US dollars millions | 2025 actual | 2026 forecast | 2027 forecast |
|---|---|---|---|
Revenue | 3.4 | 5.1 | 7.6 |
Gross margin | 62% | 64% | 66% |
EBITDA | −3.2 | −3.1 | −2.0 |
How do you check that the slide matches the model?
Diligence tests pitch deck financials against the business behind them. Baker Tilly's guide to quality of earnings studies (an accountant's review of reported earnings) notes that when an investment thesis depends heavily on management's projections, it may be necessary to widen the diligence to the competitive environment, the go-to-market strategy and customers' view of the company.
Investors test the slide against the model, so the company should do it first.
Run these six checks with the model open beside the slide. The model and the accounts it ties to belong in the data room.
Trace every figure on the slide to one cell in the model, and write the cell reference in the speaker notes.
Reconcile each historical figure to the accounts, and list every adjustment (add-back) with the line it changes.
Use one definition across slide, model and data room: customers or accounts, ARR or revenue, gross margin before or after hosting costs.
Change one assumption, such as price or growth, and confirm the forecast on the slide moves by the amount the model gives.
Keep units, rounding and year labels identical everywhere: US dollars millions to one decimal, the same fiscal year end.
Add up the ask: the raise, the spend by use and the months of runway must agree with each other and with the use-of-funds slide.
In a slide-by-slide review of a technology company's deck before its investor outreach began, we found two numbers that didn't agree with its financial model. The contract value on the business-model slide was changed to the model's figure, and a per-unit cloud cost in the model was flagged as too low for the margins the projections slide showed.
When a figure disagrees, find out which side is wrong before editing either; a slide edited to match a wrong model carries the error forward. For an owner-led company the accounts come first: EBITDA on the slide should equal the accountant's figure, with each add-back listed, because an acquirer's quality of earnings review rebuilds it.
Counsel should read the wording too. The SEC's exempt offerings FAQ states that every securities transaction, exempt ones included, is subject to the federal antifraud provisions, so the figures in a deck for a private placement fall under them. Legal review is counsel's work, and spectup doesn't give it.
How does the slide connect to the ask and the use of funds?
The ask is arithmetic on the slide: cash today plus the raise, less net spend by use, equals cash at the next milestone. The bridge below uses the example company, with cash at the end of 2025 and the 2026 and 2027 EBITDA losses from the table treated as cash.
| Step | Change | Running total |
|---|---|---|
| Cash today | $1.2M | |
| New raise | +$5.0M | $6.2M |
| Product and engineering | −$1.9M | $4.3M |
| Go-to-market | −$2.1M | $2.2M |
| Operations | −$1.1M | $1.1M |
| Cash at milestone | $1.1M |
Losses of $3.1M in 2026 and $2.0M in 2027 total $5.1M of net spend. A $5.0M raise on top of $1.2M of cash covers that and leaves $1.1M at the end of 2027. A raise the slide's own loss doesn't cover is the first thing an investor will compute.
A pre-revenue company sizes the ask the same way: monthly net spend times the months to the milestone, plus a reserve.
Where debt sits in the raise, the slide shows it on separate lines: the amount drawn, its cost and the cash needed to service it. Blended into one funding figure, equity and debt hide how much of the money has to be repaid.
The ask also sits on its own slide in the pitch deck outline, and the two must agree to the decimal.
What investors question first in pitch deck financials
I read a financials slide as evidence about the model underneath it. CB Insights found reasons for 385 of the 431 venture-backed companies it studied that shut down since 2023. Running out of capital led at 70%, almost always the final cause, with poor product-market fit (43%), bad timing (29%) and unsustainable unit economics (19%) beneath it.
A slide that shows cash and no margin leaves the investor to guess whether the money is being spent on a business that pays back.
Of the three beneath it, only unit economics is a cause a financials slide can address directly. Product-market fit and timing are judged on the market and the traction, while the 19% is answered by the margin and the unit-economics pair the slide carries.
With cash and no margin on the slide, an investor has two moves: ask for the model in the first meeting, or fill the gap with a cautious assumption. Either one hands the framing of the company's economics to the person reading it.
The margin changes how the same loss reads. In the example, revenue of $5.1M and an EBITDA loss of $3.1M in 2026 look like a heavy burn on their own. With the 64% gross margin beside them, the investor sees about $3.3M of gross profit on that revenue, and the loss becomes a question about operating costs, which the model answers line by line.
Growth is where the six checks stop short: a growth rate can tie to the model and still say little. The example's revenue rises 50% in 2026, from $3.4M to $5.1M.
Price, volume from existing customers, new customers or a sales hire can each produce that rate, and each sends the investor to a different question: churn at the new price, whether existing customers will keep buying more, the cost of acquiring the new customers, or what happens to growth when the hire's pipeline runs out.
Put the driver beside the rate. One line under the chart does it: "+50%, from new customers at a flat price".
How spectup builds the financials slide
spectup works for the company raising and builds the deck on its side, with the investor as the reader. The financials slide is made in four layers, in this order, over 12 to 19 days from the accepted proposal to the delivered deck.
Strategy, about three days on a 19-day job: the deck is argued from the investor's seat, so the offer, the investors it suits and the terms come first.
Story, about four days: the argument an investor can repeat to partners, written as prose and agreed before any slide is drawn.
Research, about five days: market size and the deals that set the comparables, each figure sourced, then the company's contracts, cohorts and unit economics rebuilt from raw data. Anything the desk can't reproduce a second time is cut.
Design, about seven days: the slide and the table above are drawn last, once the figures they carry are fixed.
A full deck starts at $5,000 per deck, fixed fee. Scope and timeline are in the proposal before work starts, and the company receives the editable deck, a PDF to send and the research appendix.
Check the slide against the model before the first investor meeting
Before the first investor meeting, run the six checks and cut the pitch deck financials slide to the figures its profile row lists. Then read it aloud against the model, figure by figure: every number you say should be one you can find in a cell, with its source and its definition.
How to talk through the slide in the room is covered in presenting the deck. Don't send the deck to anyone until every figure passes: if one fails, change the slide or the model, whichever is wrong.
Three conclusions
Choose the five or six figures by what the company can prove today. A stage label says little about whether revenue, margin or EBITDA is the number that sizes the business.
Failed-company analyses end at cash and name unit economics and product fit beneath it. A slide whose numbers tie to the model shows the unit economics were checked before the investor asks.
Cash today, the raise and net spend by use have to add up to the cash at the milestone. A gap there is the first question, and every other figure is read with that doubt.
Pitch deck financials: questions readers ask
5 questions on capital raising materials, answered by Niclas Schlopsna, Managing Partner.
01What financials should be in a pitch deck?
Five or six figures that match what the company can prove. A pre-revenue company shows its cost model, runway and milestones. A growing one shows revenue, growth, gross margin, EBITDA or burn and one unit-economics pair. A profitable one shows revenue, EBITDA, EBITDA margin, cash conversion and net debt, and every figure ties to the model.
02What do investors look for on the financials slide?
How large the business is, how fast it is moving and whether the economics hold. They then test whether the numbers tie to the model and the accounts.
03How many years should the pitch deck financial projections cover?
Up to three years of actuals and three forward years, as far as the model supports them. The first forward year should equal the current budget, since it is the one year the company can defend line by line. Years beyond the third add assumptions without evidence.
04How to show financials in a pitch deck when there is no revenue yet?
Show the cost model by month, the cash runway and the milestones the raise reaches. Add the three assumptions the plan rests on, such as price and conversion, and label them as assumptions. Leave out invented revenue: a forecast without a basis lowers trust in the rest of the slide, while a cost model with a clear runway leaves it intact.
05How much does a pitch deck with a financials slide cost?
A full spectup pitch deck starts at $5,000 as a fixed fee, with the financials slide drawn as part of it. The proposal states the scope and a timeline of 12 to 19 days, and nothing is chargeable before it is accepted.