TAM SAM SOM: Worked Examples and What Investors Test
A TAM SAM SOM example on a real count: 38,435 UK firms narrowed to a GBP 12.0M SOM, and how investors test each number from one round to the next.

TAM is what every possible buyer spends a year, SAM the part your product can serve, SOM the part you can win in the plan period.
The worked example starts from 38,435 UK medium-sized businesses (GOV.UK, start of 2025) at GBP 20,000 a year, a GBP 768.7M TAM.
Run both methods, carry the lower figure, name its source and explain the gap line by line.
Series A checks the count and the filters, Series B checks SOM against ARR and pipeline, growth investors pay for commercial due diligence.
The round pays for the sales hires that sign the customers, so the slide, the model and the use of proceeds show one number.
By the TAM SAM SOM definition, a market is sized in three nested layers, each inside the one above. TAM (total addressable market) is the revenue if every possible buyer bought; SAM (serviceable addressable market) is the part your product, price and channels can serve; SOM (serviceable obtainable market) is the share of SAM you can win in the plan period.
The TAM SAM SOM example below runs from a real count of UK companies down to the revenue a CEO or CFO has to defend in front of an investor. A marketplace, where supply caps the SOM, follows for contrast.
Investors rarely stop at the TAM. The arguments start at the two steps below it, with the filters that turn TAM into SAM and the sales plan that turns SAM into SOM, the revenue the round is paying for.
| Step | Change | Running total |
|---|---|---|
| TAM: 38,435 firms at GBP 20,000 | GBP 768.7M | |
| Outside integrations and sales reach | −GBP 461.2M | GBP 307.5M |
| SAM: 15,374 firms | GBP 307.5M | |
| Beyond year-five sales capacity | −GBP 295.5M | GBP 12.0M |
| SOM: 600 customers by year five | GBP 12.0M |
How to calculate TAM SAM SOM: what each layer measures
Each layer is one multiplication. The table puts TAM vs SAM vs SOM side by side, with the question each one answers, its formula and the input an analyst will ask you to source.
5 columns. Drag the table sideways; the first column stays put.
Layer | The question it answers | Formula | Input you must source | What an investor checks |
|---|---|---|---|---|
TAM | What would every possible buyer spend in a year? | Buyers x annual price | A dated count of buyers and a price you can evidence | Whether the count is real and the buyers are the right type |
SAM | Which part can this product, at this price, through these channels, serve? | TAM x the share that passes your filters | Each filter: geography, sector, company size, integrations | Whether every filter is written down and sourced |
SOM | What can the company win in the plan period? | Customers your sales capacity can sign x annual price | Hires, win rates, sales cycle, ramp time | Whether the capacity exists or the round pays for it |
Revenue plan | What does the model say for the same year? | Must equal SOM | The financial model | Whether the slide and the model show one number |
Each layer and its figure go on the slide, and the formula and the sourced inputs go in the appendix an analyst asks for after the meeting. The last column is your own list to check before the deck goes out.
spectup's pitch deck service sizes the market from the company's own customers and prices before a single slide is designed.
TAM vs SAM vs SOM, worked on one UK software company
Illustrative example. A UK company sells workflow software to medium-sized businesses at GBP 20,000 a year per customer.
At the start of 2025 the UK had 38,435 medium-sized private-sector businesses, firms with 50 to 249 employees, according to GOV.UK's business population estimates. At GBP 20,000 each, that's a TAM of GBP 768.7M.
Assume two filters, each with its own source. 80% of those firms sit inside the sales team's reach, from its territory map, and half of those run the systems the product integrates with, from the integration partners' published customer counts. That leaves 15,374 firms, 40% of the count, and a SAM of GBP 307.5M.
The round funds a sales team that can sign 600 customers by year five, so SOM is 600 x GBP 20,000, or GBP 12.0M, which is 3.9% of SAM.
3 columns. Drag the table sideways; the first column stays put.
Input or result | Value | Where it comes from |
|---|---|---|
UK medium-sized businesses | 38,435 | Sourced: GOV.UK, start of 2025 |
Annual price | GBP 20,000 | Assumption: signed contracts or list price |
Share passing the filters | 40% | Assumption: 80% in sales reach x 50% on the integrated systems |
Customers by year five | 600 | Assumption: the hires in the use of proceeds |
TAM | GBP 768.7M | 38,435 x GBP 20,000 |
SAM | GBP 307.5M | 15,374 x GBP 20,000 |
SOM | GBP 12.0M | 600 x GBP 20,000, 3.9% of SAM |
Here SAM is 40% of TAM, and every point of that 40% needs a reason an investor can check. The filters remove GBP 461.2M, more than half the market, and the SAM vs TAM gap is what an investor questions first.
Of the four inputs, only the 38,435 count comes from a published source. The price, the filters and the sales capacity are the company's to defend.
How do you calculate TAM top-down and bottom-up, and which figure do you carry?
Top-down and bottom-up give two numbers that seldom match, and the gap shows which assumption carries the size of the market.
Top-down sizing starts from a published total and cuts it down by country, sector and company size. For a European market, a top-down build can start from Eurostat's structural business statistics: 34 million enterprises were active in the EU business economy in 2024, and 5.4 million of them worked in professional, scientific and technical activities.
Bottom-up market sizing counts the buyers and multiplies by a price you can evidence, as the worked example did with 38,435 firms.
Top-down is fast and carries a third party's name, and it inherits every definition the report used, including segments you don't sell to.
Bottom-up takes longer, rests on a count and a price you can show, and is the version an investor can rebuild in a spreadsheet.
Reconciled puts both side by side and explains the gap line by line.
In this video I go through what investors want from a TAM now.
Illustrative example: TAM SAM SOM for a marketplace, sized from the Eurostat count. A marketplace matches EU professional-services firms with freelance specialists and keeps EUR 1,500 a year in fees from each firm that hires through it. Eurostat's 5.4 million firms in those activities give a TAM of 5.4 million x EUR 1,500, or EUR 8.1bn.
Two filters, the 40% in its three countries (an assumption here; Eurostat publishes the count by country) and the 60% that already buy freelance work (the company's own survey), leave 1,296,000 firms and a SAM of EUR 1.94bn, 24% of TAM.
In a marketplace the SOM is capped by supply. If the round funds 1,500 vetted specialists by year five, each serving 8 firms a year, SOM is 12,000 firms x EUR 1,500, or EUR 18.0M, which is 0.9% of SAM, and the investor's first question is where the 1,500 specialists come from.
Illustrative example, back to the UK company. Two paid market reports size its market at GBP 1.0bn to 1.4bn and GBP 1.2bn to 1.7bn. The bottom-up count, priced anywhere between GBP 15,000 and GBP 25,000 a year, gives GBP 577M to GBP 961M.
| Row | Low estimate | High estimate |
|---|---|---|
| Report A (Top-down) | GBP 1,000M | GBP 1,400M |
| Report B (Top-down) | GBP 1,200M | GBP 1,700M |
| This company (Bottom-up) | GBP 577M | GBP 961M |
On the decks spectup builds, when two sizing databases give different totals, the slide shows the lower one and says which database it came from. In this example the carried figure is the bottom-up GBP 768.7M, priced at the GBP 20,000 the signed contracts show, with Report A's GBP 1.0bn beside it as the cross-check.
The gap is what the reports count and the bottom-up leaves out, such as larger firms or adjacent software.
How do investors test the numbers at each round?
A Series A investor has a count and a plan to look at; a growth investor has three years of revenue and a budget for outside diligence.
Series A. Is the SAM vs TAM cut made by filters the company states, and is the bottom-up count real? The investor rebuilds the 38,435 x GBP 20,000 line and asks where the 40% comes from.
Series B. Does SOM reconcile with the ARR, pipeline, win rates and cohort retention already on the books? A plan for 600 customers needs a win rate and a sales cycle that two years of data already show.
The Series B test ends on two numbers, how big the SAM is and how much of it the plan needs; the SAM-to-TAM ratio only shows how hard the filters cut.
Shrink the SAM to GBP 60M and the same GBP 12.0M plan needs 20% of it. A GBP 40M plan on the GBP 307.5M SAM needs 13.0%, and skipping the filters, with the whole GBP 768.7M TAM used as the SAM, makes the GBP 12.0M plan look like 1.6%.
| Item | SAM size (0 to 100) | Share of SAM the plan needs (0 to 100) | Note |
|---|---|---|---|
| Worked example | 77 | 16 | GBP 307.5M SAM, GBP 12.0M SOM: 3.9% of SAM by year five. |
| GBP 60M SAM | 15 | 80 | GBP 12.0M of a GBP 60M SAM: one firm in five has to sign. |
| GBP 40M plan | 77 | 52 | 13.0% of a GBP 307.5M SAM: the hires have to be in the model. |
Growth and private equity. Commercial due diligence, an outside study of the market that the investor pays for, checks the numbers independently. In one Strategy& case for a private equity investor, the team assessed market size and penetration rates in key geographies and determined five-year growth rates.
The market build goes into the data room next to the model, where an investor's analyst rebuilds it during investor due diligence, so a number that does not rebuild costs credibility on every other number.
Which TAM SAM SOM mistakes do investors catch first?
A 2025 BCG benchmark of more than 100 private software companies notes that companies moving into adjacent categories are "also looking for a large TAM to highlight to prospective investors", and argues they should first understand their ideal customer profile and the true TAM that results.
Five mistakes an analyst can catch from the deck and its sources:
A TAM that counts buyers the product can't serve. The investor asks which of the counted firms have bought, and the answer covers one segment of the count.
One source, no date. The analyst opens the report and finds a different year, a different currency or a different definition of the market.
A SOM written as a share of the market once sales data exists. A share picked off the top of the market names no customers and no hires, and once the company has a win rate an analyst asks for both.
A SOM bigger than the sales capacity the round pays for. The check is customers per account executive per year, times the hires in the use of proceeds, the sum the worked example runs in the next chapter.
A market slide that disagrees with the model. If year-five ARR in the model and SOM on the slide differ, one of them is wrong.
Mistake 5 is settled at the pitch deck outline stage, by planning the market slide and the financials slide around one SOM before either is drawn.
Why the market slide and the financial model must show the same SOM
SOM is a revenue line the round pays for. The money hires the sales team, and the customers that team signs are the SOM.
Illustrative example. In the worked example, the round funds a team that signs 40 customers in year one, 70 in year two, 120 in year three, 170 in year four and 200 in year five. With no churn assumed, that's 600 customers and GBP 12.0M of ARR by the end of year five, 3.9% of SAM.
Three account executives already sell, and the use of proceeds hires 2, 4, 6, 4 and 2 more at the start of years one to five. Each signs 10 customers a year at full ramp and 5 in the year they join, after a six-month ramp: year one is 3 x 10 + 2 x 5 = 40, year five 19 x 10 + 2 x 5 = 200.
The same five numbers belong on the pitch deck financials slide and in the revenue tab of the model, and the use of proceeds has to show the hires that sign them. If the model shows GBP 15M of ARR at the end of year five and the slide shows GBP 12.0M, the analyst rebuilds the hires from the use of proceeds to find out which one holds.
How spectup builds a TAM SAM SOM pitch deck slide
spectup works for the company raising the round, and the investor is the reader the slide has to convince. Market research is the third step of the deck work, after strategy and story and before design, and our consultants run it.
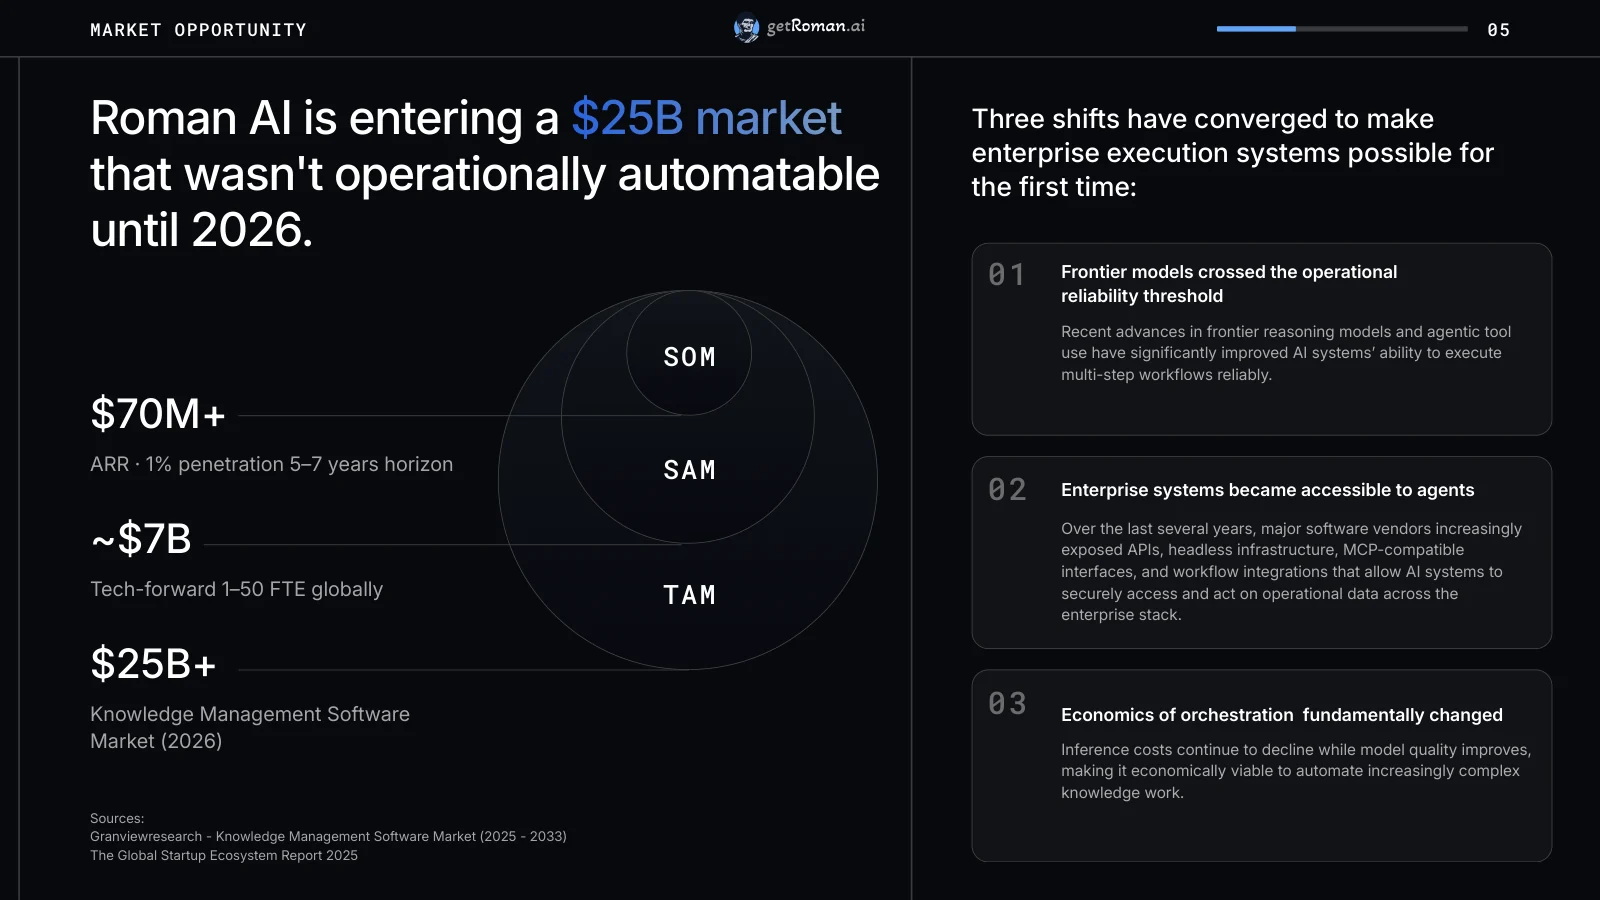
The slide above puts a $25B+ knowledge management software market (2026) as TAM, about $7B for tech-forward companies of 1 to 50 staff worldwide as SAM, and $70M+ of ARR at 1% penetration over five to seven years as SOM. The two sources printed at the foot are a Grand View Research report on the knowledge management software market (2025 to 2033) and “The Global Startup Ecosystem Report 2025”.
Its SOM is a share, 1% of the SAM over five to seven years, with no hires shown on the slide. At seed that is as far as the evidence goes, because there is no win rate or sales cycle yet to price a sales team against.
From the first round with sales data, an analyst asks which hires sign that 1%, and the build in the worked example replaces the share.
A full market build has four layers, each sourced on its own and each a line on the slide.
Total market where the company sells, the TAM, from two licensed sizing databases reconciled against each other.
The segment that can buy, the SAM, from filings and registry counts.
What's reachable inside the plan period, the SOM, from the company's own coverage and sales capacity.
What's held today, the revenue already under contract, from the signed contracts.
A figure a second source can't confirm comes off the slide. The same research covers the competitive map, with doing nothing plotted as an alternative, and the macro context, with a source behind every number.
A robotics company briefed us with notes from its earlier investor pitches: how hard the system was to move to a new crop, that market claims had to name their source on the slide, and an earlier turn-down for sounding too narrow. We made a teaser deck to send ahead and a presentation version to take into the meeting, and the client approved both.
The research is covered by the engagement and priced into the pitch deck cost, and after delivery spectup can also take the deck to investors.
Choose the SOM you can defend before you choose the TAM
Build the TAM SAM SOM slide in reverse. Start with SOM. That is the hires the round pays for, the customers they can sign each year and the price in your signed contracts.
Size SAM next, from a dated count, and write down every filter with its source. Let the TAM be whatever the sources say, even when it's smaller than the number you hoped to show.
Then put the slide through the four checks an analyst makes before writing the investment memo a committee reads:
Is the count under your TAM sourced and dated, the way 38,435 is from GOV.UK?
Is every filter between TAM and SAM written down, with a source an analyst can open?
Does SOM equal the model's ARR at the end of year five, customer for customer?
Could an analyst rebuild every number from your appendix without calling you?
In the worked example, a team growing from 5 to 21 account executives over five years signs the 600 customers that put GBP 12.0M on the slide and in the model.
Three conclusions
A TAM built from a dated count and a price you can evidence survives an analyst's rebuild. A single report figure invites the question of what it counts that the company can't sell to.
SOM is the customers the round's sales capacity can sign, times the price. Once there are win rates to price, a SOM picked as a share of the market won't match year-five revenue in the model, and an analyst checks the two against each other.
A GBP 307.5M SAM with every filter sourced reads stronger to an investor than a multi-billion TAM taken from one report, because each layer can be checked and kept.
TAM SAM SOM: questions readers ask
8 questions on capital raising materials, answered by Niclas Schlopsna, Managing Partner.
01What is the difference between TAM, SAM, and SOM?
Each is a narrower cut of the one above. TAM is what every possible buyer spends in a year, SAM is the part your product, price and channels can serve, and SOM is the part you can win in the plan period. The step from TAM to SAM shows your filters, the step from SAM to SOM your sales capacity.
02How do I calculate TAM, SAM, and SOM?
Start with a dated count of the buyers you could sell to and multiply it by an annual price you can evidence. The product is your TAM. Apply each filter you can state, such as sector, company size, geography or integrations, to get SAM. Once you have sales data, build SOM from the customers your sales capacity can sign in the plan period, times the same price; before that, a modest share of a sourced SAM is as far as the evidence goes. Then check the total against a top-down figure and explain the gap.
03How do I calculate market sizing?
Two ways, and a credible deck runs both. Top-down cuts a published total, such as Eurostat's count of EU enterprises, by country, sector and company size; bottom-up multiplies a count of buyers by a price you can evidence.
04Can you give me an example of a TAM, SAM, and SOM?
Illustrative example: 38,435 UK medium-sized businesses (GOV.UK, start of 2025) at an assumed GBP 20,000 a year give a TAM of GBP 768.7M. If 40% pass the reach and integration filters, SAM is GBP 307.5M; a sales plan for 600 customers by year five gives a SOM of GBP 12.0M.
05Is there a TAM SAM SOM template I can use?
Yes. The layer table under How to calculate TAM SAM SOM works as one, with each layer and its figure on the slide and the formulas in the appendix.
06What is TAM SAM SOM, and what do the letters stand for?
TAM SAM SOM is a three-layer market sizing method: total addressable market, serviceable addressable market and serviceable obtainable market.
07What does 30% market share mean?
It means one company takes 30% of all the spending in its defined market. As a SOM that's a high bar. In the worked example, 30% of the GBP 307.5M SAM would be GBP 92.2M a year, nearly eight times what the sales plan supports.
08When should a company bring in a pitch deck service to build its market sizing?
When the market slide has to survive an analyst rebuilding it. spectup's Pitch Deck Services build the sizing from the company's own customers and prices and carry the lower figure where two databases disagree.