Pitch Deck vs Business Plan: Which to Write First
Pitch deck vs business plan for a raise or a sale: the deck earns the first meeting, the plan answers the reader after yes. Who asks for which, and when.

Reader, question, length and first read for each document, with the figures from DocSend, J.P. Morgan and the SBA.
Which reader asks for the deck, the business plan or the memorandum, and at which point in the process.
The deck earns the first meeting, the model sits beside it, and the plan follows when someone asks.
A traceability table links each deck claim to a plan section and a file in the data room.
Decks start at $5,000 on a fixed fee and take 12 to 19 days from an accepted proposal.
Pitch deck vs business plan is a question of order: the deck earns the first meeting, and the business plan answers what a reader asks after saying yes. Write the deck first, build the financial model beside it, and write the plan when a lender or an investor in diligence asks for it.
The exception is a raise where the first reader is a lender: there the plan goes first, because lenders commonly request one.
| Track | What | When |
|---|---|---|
| Pitch deck | 0 to 45 sequence only, not days | |
| Financial model | 0 to 100 sequence only, not days | |
| Data room | 0 to 100 sequence only, not days | |
| Business plan | 45 to 100 sequence only, not days | |
| M&A memorandum | 45 to 100 sequence only, not days |
Pitch deck vs business plan: the differences in one table
Investors spend less than three minutes on a deck, according to DocSend's data; J.P. Morgan's guidance quotes one of its bankers saying that some people will say 10 slides and some 12, and the SBA says a traditional plan can run to dozens of pages and a lean plan is typically one.
4 columns. Drag the table sideways; the first column stays put.
Pitch deck | Business plan | M&A memo | |
|---|---|---|---|
Reader | An investor deciding on a second meeting | A lender, an investor in diligence, or the company's own team | A strategic or sponsor buyer deciding whether to bid |
Question it answers | Is this story worth more time? | Does the operation behind the story hold up? | What is for sale, and on which normalized earnings? |
Length | Roughly 10 to 12 slides | Dozens of pages (traditional), one page (lean) | Set by the segments, sites and years of financials |
First read | Under 3 minutes | Read in full once the reader is in diligence | Read before the bid |
Requested | For the first meeting | After interest is confirmed, or when a lender asks | Once a buyer has confirmed interest in a sale |
If missing | The meeting doesn't happen | Diligence waits, or the lender's request goes unanswered | Buyers have nothing to bid from |
The difference between a pitch deck and a business plan shows in the first-read row: only the deck is judged by a stranger on a first read.
What is a pitch deck in business, and what does a business plan add?
A deck has to win the first meeting. The plan shows how the operation delivers what the deck promises, and the financial model under both holds the arithmetic.
spectup's pitch deck service builds the deck, the document a stranger judges. A deck carries five things:
the problem and the market it sits in
the product and how it earns money
traction, in numbers a reader can check
the team
the ask, with the amount and the use of proceeds
A plan carries what the slides have no room for:
the hiring roadmap and the organization behind it
the sales channels and how each one is run
the risks and what is done about each
the assumptions under every line of the model, written out
Every claim on a slide has a counterpart in the plan: the revenue figure on the traction slide traces to the revenue build, and the plan holds the working.
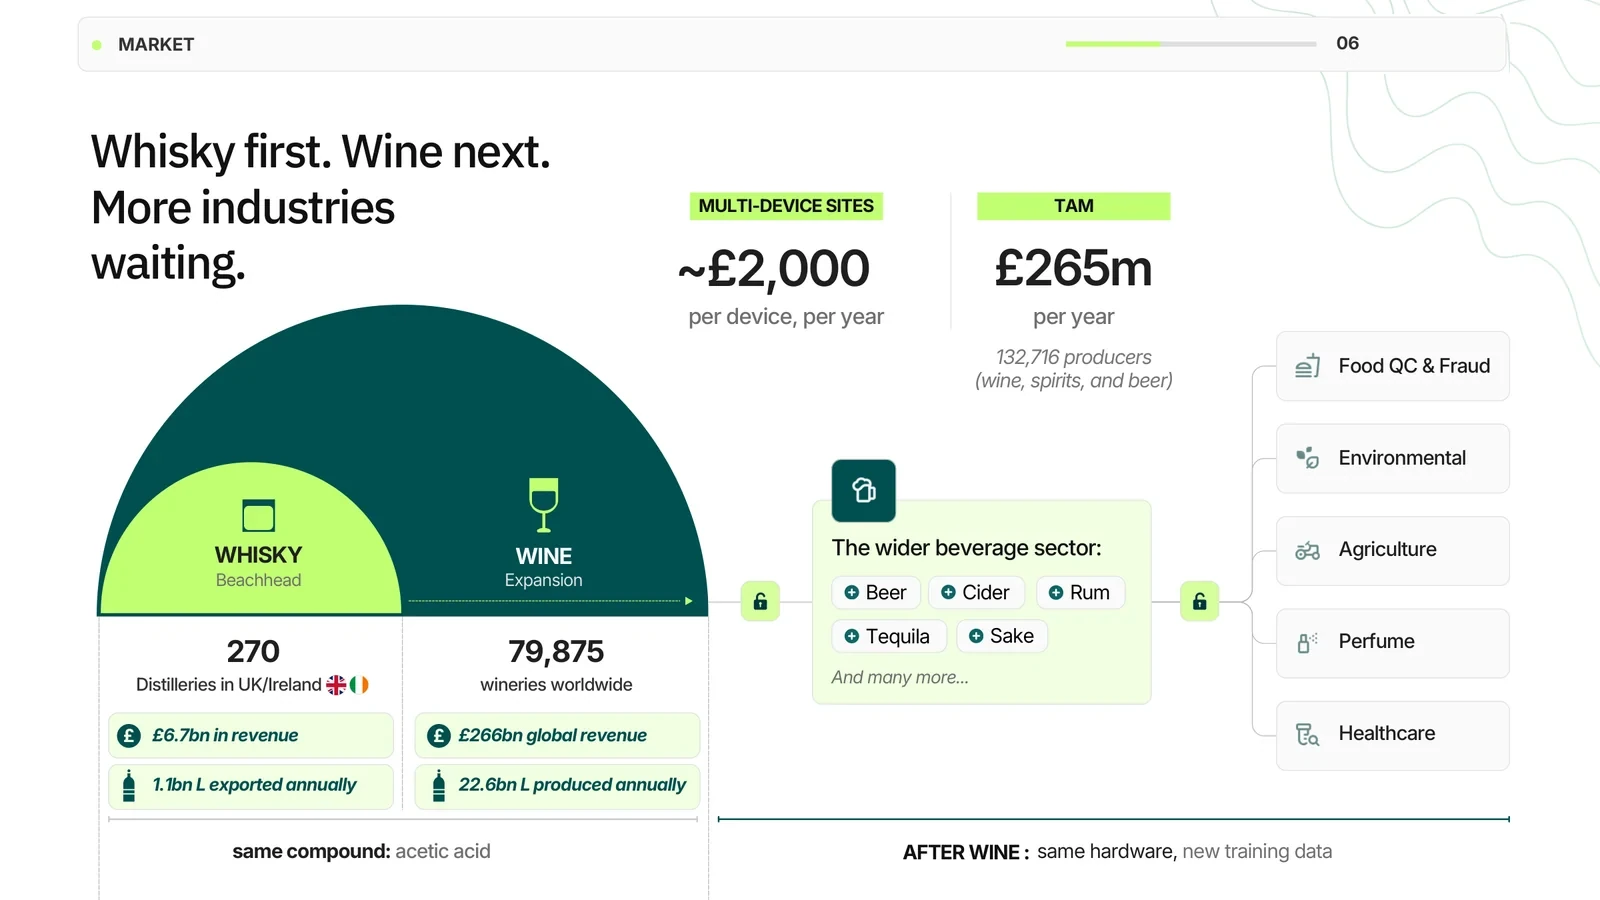
The market slide above prints a TAM of £265m a year beside the two figures that build it, about £2,000 per device a year across 132,716 producers. A plan behind a slide like this holds where each of those two figures comes from.
Are business plans text-based documents?
Mostly: a traditional plan, which the SBA puts at dozens of pages, is text on the operation, the hiring and the risks, with the model's revenue build and cash position set in as tables.
Are business plans highly visual? Rarely. A plan carries a chart where a model figure needs one, such as the revenue build; the pictures sit on the slides.
What the financial model carries
The financial model holds the figures both documents quote: the revenue build, the cost base, the cash position and the use of proceeds. When a reader challenges a number, the answer comes from the model.
Business plan vs pitch deck: which readers ask for which?
The decision in front of the reader picks the document: an investor at a first meeting decides whether to continue, a lender decides whether the business can repay, and a buyer decides whether to bid.
| Item | Depth of reading (0 to 100) | Reliance on the plan (0 to 100) | Note |
|---|---|---|---|
| Investor, first meeting | 10 | 8 | Deck |
| Investor, diligence | 72 | 58 | Model, data room, plan |
| Lender | 60 | 92 | Plan |
| Buyer, before bidding | 92 | 34 | Memorandum |
| Management team | 34 | 82 | Plan |
The same investor changes document once interest is confirmed. In diligence the request is for the model and the data room, and often the plan with them.
A lender starts with the plan. On the traditional business plan, the SBA writes: "Lenders and investors commonly request this plan."
The management team needs a plan whichever outside reader is waiting, because it holds the hiring and channel decisions the deck leaves out. That plan is also the one document of the three that gets reread internally after the money arrives.
Pitch deck vs business plan: which should a company write first?
Write the deck first and build the financial model with it.
A banker quoted in J.P. Morgan's guide for investor decks says "In many ways, your pitch deck has replaced the old days of a lengthy business plan".
A business plan pitch deck, meaning slides cut down from a finished plan, keeps the plan's order, which follows the operation. A reader's order follows the decision: what's this, why now, what's it worth, what's the ask.
From the desk. A deck is read by someone with no time to ask questions, so its case has to rest on figures a reader can check. With $760M+ advised, raised or placed, spectup builds pitch decks, fund decks, real estate decks and M&A memos.
The investor presentation we built for a beverage brand's $4.5M round argued the case on shelf economics, and the round was raised.
If the plan already exists and the business plan pitch deck is a cut-down of it, work in the reverse of the order it was written. Pick the claims a stranger can judge in three minutes, put them on slides, and file the plan's evidence in the data room. Those claims set the deck's length, whatever the plan's page count.
A working order for the deck-first route:
Fix the five claims a stranger has to accept, with the ask on top.
Build the model for those claims only, and keep its assumptions on one page.
Draft the slides from the claims, in the order the reader decides, using the pitch deck outline.
File the proof for each claim in the data room before the first meeting.
Write the plan when someone asks for it, from the model and the filed proof.
How do the investor pitch deck and business plan stay consistent?
One model feeds both documents. A figure on slide nine should trace to the model and to a file a reader can open, and to its plan section once a plan is written.
3 columns. Drag the table sideways; the first column stays put.
Deck claim | Plan section, once written | Proof the reader can open |
|---|---|---|
Revenue and growth on the traction slide | Financial plan, revenue build | Management accounts and the model's revenue tab |
Market size | Market and competition | The report behind the figure |
Use of proceeds in the ask | Funding plan | The budget in the model |
Key hires on the team slide | Organization and hiring plan | Contracts and the organization chart |
Named customers or pipeline | Sales and channel plan | Customer contracts and the CRM export |
| Step | Change | Running total |
|---|---|---|
| Recognized revenue (plan) | $11.6M | |
| Contract signed after year end | +$0.4M | $12.0M |
| Deck figure incl. contract | $12.0M |
Illustrative example: the deck shows $12.0M because it counts a contract signed after the year end, while the plan's revenue build shows $11.6M of recognized revenue. The two figures measure different things, and a reader who finds the $0.4M gap asks which document is wrong. Put a footnote on both that names the measure and the cut-off date.
When a number moves, change the model first, then reissue the deck, the plan and any memorandum on the same day and date each version, so nobody quotes last month's figure.
The SEC's guidance on exempt offerings says "All securities transactions, even exempt transactions, are subject to the antifraud provisions of the federal securities laws", and what is said to investors falls under it. When a reader lays the deck's figures next to the plan's, a mismatch on revenue, or a memorandum that disagrees with both, leaves a question to answer.
Investors test the same numbers in investor due diligence, usually against the data room.
Pitch deck vs business plan in a sale: the buyer reads a memorandum
In a sale the plan's job passes to the information memorandum, the document a buyer reads before bidding. The company is the client, and the buyer is brought to the table.
spectup writes the memorandum for a strategic and a sponsor at once, with positioning and normalized financials, and a sell-side M&A process goes to market with it.
| Step | Leads to |
|---|---|
| Accounts and model (Company figures) | Vendor diligence reports |
| Vendor diligence reports (Earnings, working capital, contracts) | Memorandum [Same figures] |
| Memorandum (Positioning and normalized financials) | Strategic buyer; Sponsor buyer |
| Strategic buyer | end |
| Sponsor buyer | end |
An investor in a raise reads forward, through the plan, the use of proceeds and the return. A buyer reads backward first: normalized earnings, working capital and contracts, and only then the forecast.
A buyer prices the company from the memorandum, so its figures have to match the reports behind it. KPMG's guidance for sellers says a vendor due diligence report typically covers a quality of earnings analysis (how much of the profit repeats), a working capital review and a key contract analysis.
The same guidance tells a seller to begin gathering its financial records, projections included, "well in advance of any buyer requests", and to keep them in a structured data room.
Business plan vs pitch deck: when the plan comes first
Beyond a lender's request, the plan leads in a regulated or operations-heavy business, where licenses and capacity are the case, and inside a team that needs one roadmap before it can agree on a number for the deck.
A deck written before that agreement tends to carry whichever figure the last meeting settled on. Where a company is for sale, the plan can become the confidential information memorandum.
A plan nobody has asked for, written before the model exists, delays the one document a stranger will read.
How spectup runs a pitch deck engagement
spectup acts for the company or the fund that is raising or selling, and brings the investor or buyer to the table. It builds four documents, and each has a different reader:
a pitch deck, read by an investment committee without the company in the room
a fund deck, read by an allocator in a queue of similar decks
a real estate deck, read by a credit committee that checks every number against its own model
an M&A memo, read by a buyer
A deck engagement works in four layers, with the design last:
Strategy: what's being sold, to whom and on what terms, decided from the reader's side first.
Story: the argument the reader repeats internally, agreed before anything is drawn.
Research: sizing and comparables with a source behind every figure.
Design: slides drawn to be presented in a fifteen-minute slot and to hold up when forwarded as a PDF.
Decks start at $5,000 each on a fixed fee, and delivery takes 12 to 19 days from an accepted proposal. The same figures then carry into the memorandum when the engagement is a sale or a fund placement.
For a fund or a private placement, spectup drafts the private placement memorandum, and the legal and regulatory sections go to securities counsel for review.
Choosing the first document for your next investor or buyer meeting
Pitch deck vs business plan is a choice made per meeting. Name the meeting first, then the decision the reader has to make, and then pick the document.
Before any of them goes out, two things have to exist: the model, and one data-room folder for each claim. Open your model, list the five figures your deck states, and check that each one appears in the model and in a file a reader can open. When the plan is asked for, it reads from the same cells.
Three conclusions
An investor at a first meeting asks for a deck, a lender asks for a plan and a buyer asks for a memorandum. Name the reader and the decision before choosing the document, and the order follows.
Every figure in the deck, the plan and the memorandum should trace to the same model and to a file in the data room. Antifraud rules apply to what investors are told, so documents that disagree leave a question to answer.
A stranger judges the deck in under three minutes, so it is written first. The plan is built when a lender, an investor in diligence or the management team asks for it.
Pitch deck vs business plan: questions readers ask
6 questions on capital raising materials, answered by Niclas Schlopsna, Managing Partner.
01Is a pitch deck a business plan?
No. The deck wins a first meeting; the plan explains how the company operates and delivers. Both read from one financial model.
02What is the difference between a pitch deck and a business plan?
A stranger reads a deck in under three minutes, and it holds roughly 10 to 12 slides. A traditional business plan runs to dozens of pages and is read in diligence, by a lender or by the company's own team.
03Which should a company write first, pitch deck or business plan?
The pitch deck, with the financial model built beside it. The business plan follows when a lender or an investor in diligence asks for it, or when the management team needs a roadmap. If a plan already exists, lift its strongest claims into the deck and file the evidence in the data room.
04Can a pitch deck replace a business plan?
For a first meeting, yes: the deck carries the story and the model carries the numbers, and a deck built that way is enough to start. It doesn't replace a plan when a lender asks for one, when the team needs an operating roadmap or when a sale calls for a memorandum.
05How do you keep an investor pitch deck and business plan consistent?
Build one financial model and let every document read from it. Trace each figure on a slide to a section of the plan and to a file in the data room before anything goes out. When a number moves, change the model first, then update the deck, the plan and any memorandum in the same sitting, and date each version so a reader can tell which is current.
06What does it cost to have a pitch deck built for a raise or a sale?
spectup's pitch deck service starts at $5,000 a deck on a fixed fee, and delivery takes 12 to 19 days from an accepted proposal. It builds pitch decks, fund decks, real estate decks and M&A memos. A business plan is not one of the four.