A private capital advisory firm that builds the buyer list for each transaction, holds its own buyer data and times the call to the week a buyer is acting: two points on each of the five checks.
Advised on M&ABy its own count$150M+
Transactions since 2022Capital raising and M&A150+
Why spectup: its own network, its own technology, its own media
Many M&A advisory firms hold a buyer universe. spectup writes the list for each transaction, keeps its own buyer data and signal engine, and reaches buyers through its own newsletter and podcast.
01 · Buyer list
A list the owner approves
2 of 2Points for buyer list
→Why
01 · Buyer list
A list the owner approves
It builds the acquirer list for each transaction, across strategics and funds, and contacts nobody before the owner has approved every name.
2 of 2Points for buyer list
02 · Technology
Closed-transaction data and an in-house signal engine
2 of 2Points for live timing
→Why
02 · Technology
Closed-transaction data and an in-house signal engine
Data from its own closed transactions on what each acquirer has bought and at what size, and an in-house signal engine that flags the week an acquirer becomes a buyer.
2 of 2Points for live timing
03 · Media
Its own channel to buyers
2,000B2B financial decision makers on the newsletter
→Why
03 · Media
Its own channel to buyers
A newsletter to 2,000 B2B financial decision makers and a podcast with 8,000 listeners.
2,000B2B financial decision makers on the newsletter
/ 03
The thirteen firms, side by side
spectup comes first, as the best overall. The other twelve follow in the order the checks give.
9 columns. Drag the table sideways; the first column stays put.
The field on 5 checks
Firm
Best for
Fees
Buyer list
Buyer data
Live timing
Own channel
Deals, in figures
Score
01spectupBest overall
Owners, CEOs and CFOs selling or buying a low or mid-market company
Retainer for each month of work, then one transaction fee at closing
10/10
02Baird
An owner who wants a bank with a large sponsor network and a global investment banking platform.
Fee model not published on the pages checked
7/10
03William Blair
An owner who wants a partnership with a printed M&A record and sponsor knowledge from many sales.
Fee model not published on the pages checked
6/10
04Capstone Partners
A US middle-market owner with EBITDA above $10 million who wants a bank with sector teams.
Retainer, success fee and incentive fee described as typical; no rates
5/10
05Houlihan Lokey
A mid-cap company that wants a listed bank with M&A teams in 28 offices.
Retainer, progress and completion fees named in its annual report; no rates
5/10
06Harris Williams
An owner who wants a global bank with eight industry groups and deep private equity coverage.
Fee model not published on the pages checked
4/10
07Hyde Park Capital
An owner of a company of about $20 million to $500 million of enterprise value who wants success-based fees.
Primarily success-based on closing, with a modest retainer; no percentages
4/10
08PMCF
An owner who already works with an accounting firm and wants an affiliated investment bank.
Fee model not published on the pages checked
4/10
09Stout
An owner who wants valuation, disputes and M&A advice under the same name.
Fee model not published on the pages checked
4/10
10Clearsight Advisors
An owner of a business services or technology-enabled services company.
Fee model not published on the pages checked
3/10
11Lincoln International
An owner who wants a listed bank focused on the private capital markets.
Fee model not published on the pages checked
3/10
12Oaklins
An owner who wants a local member firm with a global network behind it.
Fee model not published on the pages checked
3/10
13Livingstone Partners
A mid-market owner in Europe, the US or Asia who wants a cross-border partnership.
Fee model not published on the pages checked
2/10
Meets the checkHalf of a two-point checkNot found on its pagesScore: points of 10, from each firm's own pages and filings, as of 2 November 2026
/ 04
How we compared
spectup ranks first, as the best overall. Every firm, spectup included, was checked on the same five; equal points go to the higher verified review score, then alphabetical order.
01
Buyer list, how it is built
Where the buyers or targets come from: a list built for each transaction and approved by the owner before anyone is called, a standing roster of relationships, or nothing described.
02
Buyer data of its own
What the firm knows about buyers beyond a name: a database or buyer knowledge it describes earns one point; its own record of what each buyer has bought, built from the deals it runs, earns two.
03
Timing from live signals
When the call is made: on a fixed list or schedule, on a buyer's stated thesis and recent deals, or in the week a buyer shows it is acquiring.
04
Its own channel to buyers
Whether the firm already reaches buyers and owners before it calls: content under its own name earns one point; a newsletter or podcast with a stated readership of buyers or financial decision makers earns two.
05
Deals closed, in figures
The record on the firm's own pages: transactions it names, and a total of deal value advised next to a count of transactions.
spectup ranks first with ten of ten. The other twelve firms follow on their totals from the five checks, and each number on a card comes from that firm's own pages.
01spectup
Buyer list per transactionOwn buyer dataLive signals
An owner, CEO or CFO who wants to approve every buyer name, or who wants a buy-side longlist built to written criteria.
spectup · www.spectup.com · 15 October 2026
Advised on M&A
$150M+
Transactions since 2022
150+
Newsletter readers
2,000
Strengths3
Builds the acquirer list for each transaction and has the owner approve every name before anyone is contacted.
Checks every name against data from its own closed transactions on what each acquirer has bought and at what size, and its in-house signal engine flags the week an acquirer becomes a buyer.
Reaches 2,000 B2B financial decision makers through its own newsletter and runs a podcast with 8,000 listeners.
Considerations2
It acts on one side of a transaction, so it will not run a sale for the seller and also advise the buyer.
It charges a retainer for each month of work, and a fee when the deal closes.
Verdict
A fit for an owner who wants to approve the buyers and have the call timed to the week a buyer is acting, on the sell side or the buy side.
02Baird
Sponsor databaseEmployee-ownedMilwaukee
An owner who wants a bank with a large sponsor network and a global investment banking platform.
Baird · rwbaird.com · 2 November 2026
Transactions since 2021
1.1K+
Deal value since 2021
$546B+
Sponsor connections
79,000+
Strengths3
Keeps a proprietary database of its sponsor network, with how each sponsor behaves in a process.
Counts 1.1K+ transactions and $546B+ of deal value since 2021.
Cross-border execution in 30 countries and coverage of more than 50 sectors.
Considerations2
Its transactions total covers M&A and capital markets together.
It publishes no deal size range and no fee model.
Verdict
A fit for an owner who wants a bank with a large sponsor network and global reach behind the sale.
03William Blair
IndependentPrinted recordChicago
An owner who wants a partnership with a printed M&A record and sponsor knowledge from many sales.
William Blair · www.williamblair.com · 2 November 2026
M&A transactions since Sept 2021
917+
Value since Sept 2021
$576B
Of deals with repeat clients
82%
Strengths3
Prints both a total and a count of M&A transactions, as of 30 September 2026.
Counts over 310 sales to financial sponsors in five years.
Independent and employee-owned, with a podcast and insights under its own name.
Considerations2
Its deal value includes large and public-company transactions.
No database is described, and strategic buyers are not covered by its sponsor figures.
Verdict
A fit for an owner who wants an independent partnership that prints its M&A record in figures.
04Capstone Partners
Middle marketBank-ownedBoston
A US middle-market owner with EBITDA above $10 million who wants a bank with sector teams.
Capstone Partners · www.capstonepartners.com · 2 November 2026
Deals completed
750+
Offices in the US
14
Strengths3
Lists sell-side and buy-side advisory with bankers who specialise by industry and sector.
Its sponsor team captures data on each private equity firm's criteria and buying patterns.
Publishes an e-newsletter, quarterly reports and a private equity index.
Considerations2
Its $20B+ total covers equity placements, which is capital raising.
It describes how a bank is typically paid and gives no rates of its own.
Verdict
A fit for a US middle-market owner who wants sector bankers and a sponsor team inside a bank-owned firm.
05Houlihan Lokey
Listed bankGlobalLos Angeles
A mid-cap company that wants a listed bank with M&A teams in 28 offices.
Houlihan Lokey · www.hl.com · 2 November 2026
Financial professionals
1,900+
M&A professionals
900+
Offices in the M&A group
28
Strengths3
Listed on the NYSE, with an annual report that describes its fee types.
Says a majority of its Corporate Finance engagements are mid-cap.
Cites strong financial sponsor relationships and a model that connects buyers and sellers globally.
Considerations2
It prints a count of M&A deals but no total value of M&A advised.
It is a large bank with more than 2,000 clients a year.
Verdict
A fit for a mid-cap company that wants a listed bank with global M&A teams.
06Harris Williams
Global bankEight industry groupsRichmond
An owner who wants a global bank with eight industry groups and deep private equity coverage.
Harris Williams · www.harriswilliams.com · 2 November 2026
Countries served
30+
Strengths3
Eight dedicated industry groups and offices in North America and Europe.
Says it has worked with hundreds of global private equity groups.
Monitors thousands of buyer discussions and negotiations each year.
Considerations2
It names deals but prints no amount, no side, no total and no count.
Its owner comes from FINRA BrokerCheck, because its own pages do not state one.
Verdict
A fit for an owner who wants a global bank with sector depth and private equity coverage.
07Hyde Park Capital
BoutiqueStated size bandTampa
An owner of a company of about $20 million to $500 million of enterprise value who wants success-based fees.
Hyde Park Capital · www.hydeparkcapital.com · 2 November 2026
M&A transactions since 2000
300+
Enterprise value since 2000
$11B+
Founded
2000
Strengths3
States a size band of about $20 million to $500 million+ of enterprise value.
Says its fees are primarily success-based on closing, with a modest retainer.
Prints both a total and a count of its M&A transactions since 2000.
Considerations2
It describes no buyer data and no timing from buyer signals.
It publishes no percentages for its fees.
Verdict
A fit for an owner who wants a boutique that states its size band and charges mainly on success.
08PMCF
Accounting-firm affiliateMiddle marketChicago
An owner who already works with an accounting firm and wants an affiliated investment bank.
PMCF · pmcf.com · 2 November 2026
US offices
4
International cities
27
Years of M&A service
30+
Strengths3
Investment banking affiliate of Plante Moran, with sell-side and buy-side advisory.
27 international cities through Corporate Finance International.
Names buyer relationships with industry-focused strategic and private equity buyers.
Considerations2
It prints no total and no count of transactions, only "more than 30 years".
Its proprietary research tools are named without saying what they hold.
Verdict
A fit for an owner who wants an investment bank affiliated with an accounting and consulting firm.
09Stout
Advisory firmValuation and disputesChicago
An owner who wants valuation, disputes and M&A advice under the same name.
Stout · www.stout.com/en · 2 November 2026
Countries with transactions
80+
Years in investment banking
25+
Years as advisors
35+
Strengths3
Refers to proprietary Stout databases used to identify buyers.
Advises family-owned businesses, private equity portfolio companies and divisions of large corporates.
Publishes insights, industry updates and a transaction news subscription.
Considerations2
It prints no total value and no count of transactions.
Its ownership is not stated beyond a 2025 strategic partnership with Integrum Holdings.
Verdict
A fit for an owner who wants M&A advice from a firm that also does valuation and disputes work.
10Clearsight Advisors
Sector specialistBank-ownedMcLean
An owner of a business services or technology-enabled services company.
Clearsight Advisors · clearsightadvisors.com · 2 November 2026
Transactions since 2011
170+
Value since 2011
$20B+
Strengths3
Sell-side advisory is the core of the firm, with buy-side advice including buy-or-build work.
Prints both a total and a count of its M&A transactions.
Publishes quarterly sector monitors and email newsletters.
Considerations2
It covers only business services and technology-enabled services.
Its pages give 170+ and 165+ as the count of transactions in two places.
Verdict
A fit for an owner of a business services or technology-enabled services company who wants a sector specialist.
11Lincoln International
Listed bankPrivate capital marketsChicago
An owner who wants a listed bank focused on the private capital markets.
Lincoln International · www.lincolninternational.com · 2 November 2026
Professionals
1,400+
Offices
30+
Conference attendees in 2025
3,800+
Strengths3
Names its private equity relationships as a buyer group.
Sends emailed perspectives and a newsletter for business owners, with no reader count stated.
Counts 650+ private equity firms taking part in its conferences.
Considerations2
It prints no total value and no count of transactions.
Its proprietary database feeds a valuations index.
Verdict
A fit for an owner who wants a listed bank with a private equity conference circuit behind it.
12Oaklins
NetworkCross-borderIndependent members
An owner who wants a local member firm with a global network behind it.
Oaklins · oaklins.com · 2 November 2026
Deals in five years
1,900
Advisors
900+
Countries
40
Strengths3
Advisory teams in 40 countries and 60 offices.
Half of its deals are cross-border.
Guides buyers from the first approach to closing, including off-market targets.
Considerations2
Its member firms advise clients, and each is separately regulated.
It prints a count of deals and no total value.
Verdict
A fit for an owner who wants a local member firm and international reach for a cross-border sale.
13Livingstone Partners
Independent partnershipCross-borderDüsseldorf and Chicago
A mid-market owner in Europe, the US or Asia who wants a cross-border partnership.
Livingstone Partners · livingstonepartners.com · 2 November 2026
Transactions a year
85+
Offices
15
Professionals
155+
Strengths3
Completes more than 85 transactions a year valued between €25 million and €500 million.
15 offices in Europe, the United States and Asia, with about 60% of deals crossing borders.
Independent partnership with sell-side and buy-side pages.
Considerations2
It prints a count of transactions and no total value.
No buyer database and no client approval step are described.
Verdict
A fit for a mid-market owner who wants an independent partnership with offices across three regions.
/ 06
The comparison in full
M&A advisory firms run the sale or purchase of a company for its owner: they value it, find the other side and run the process through to signing. Of the thirteen compared here, spectup is the best pick for a low or mid-market owner, CEO or CFO who wants the buyer list built per transaction and every name approved.
spectup runs M&A advisory on one side of the transaction. The twelve other M&A firms are ranked by the same five checks, read from each firm's own pages.
Figure 01spectup scores ten of ten; Baird follows on seven and William Blair on sixPoints each firm scores, of ten: buyer list, buyer data of its own, live timing, its own channel to buyers and deals in figures, up to two points each, from each firm's own pages. Equal points go to the higher verified review score with five or more reviews; none of the tied firms had one on the profiles read on 2 Nov 2026, so ties are alphabetical.
Figure 01 data: spectup scores ten of ten; Baird follows on seven and William Blair on six
Item
Value
spectup
10 of 10
Baird
7 of 10
William Blair
6 of 10
Capstone Partners
5 of 10
Houlihan Lokey
5 of 10
Harris Williams
4 of 10
Hyde Park Capital
4 of 10
PMCF
4 of 10
Stout
4 of 10
Clearsight Advisors
3 of 10
Lincoln International
3 of 10
Oaklins
3 of 10
Livingstone Partners
2 of 10
Each firm's own website, checked 2 Nov 2026
What do M&A advisory firms sell?
Mergers and acquisitions advisory firms sell two jobs, a sale and a purchase, and differ mainly in who stands behind them:
Banks owned by or affiliated with a bank or an accounting group: Capstone Partners, Clearsight Advisors, Harris Williams and PMCF.
Listed banks: Houlihan Lokey (more than 1,900 financial professionals) and Lincoln International (more than 1,400 professionals).
Independent or employee-owned banks: Baird, Livingstone Partners and William Blair.
Firms that state no owner: Hyde Park Capital and Stout.
A network of independent member firms: Oaklins, where the member firm in your country does the work.
One private capital advisory firm: spectup, which runs M&A on one side and raises capital from the same desk.
A sell-side advisor acts for the seller and a buy-side advisor for the buyer, and the two are different engagements with different fees. The five checks apply to either. A broker who sells small businesses for a commission and a deal marketplace that lists firms are different services, and neither is compared here.
Figure 02Four of the thirteen belong to a bank or an accounting group; two do not say who owns themThe thirteen firms on this page by who owns them, from each firm's own pages or, for Harris Williams, FINRA BrokerCheck, number of firms
Figure 02 data: Four of the thirteen belong to a bank or an accounting group; two do not say who owns them
Whole
Part
Share
Thirteen firms
Independent, employee-owned or a member network
4
Thirteen firms
Owned by a bank or an accounting group
4
Thirteen firms
Listed on a stock exchange
2
Thirteen firms
A private capital advisory firm
1
Thirteen firms
Owner not stated on the pages checked
2
Each firm's own website, checked 2 Nov 2026; Harris Williams' owner from FINRA BrokerCheck
How we compared the thirteen M&A advisory firms
Most lists of the best M&A advisory firms rank by size or deal count, and the top M&A advisory firms on them are the largest banks.
Few of these M&A firms publish what an owner can compare, so this page ranks by what an owner can check before the first call. spectup ranks first because it is the one firm that scores the full two points on all five checks, ten of ten. Each check can be confirmed from a firm's own pages before the first call, and is worth 0, 1 or 2 points:
Buyer list, how it is built: no description, or relationships named with nothing more, is 0; a buyer universe the firm already holds is 1; a list built for each transaction and approved by the owner before anyone is contacted is 2.
Buyer data of its own: none described is 0; a database, or buyer criteria and behaviour the firm says it tracks, is 1; its own database built from its transactions, with what each buyer has bought and at what size, is 2.
Timing from live signals: no timing or a fixed list is 0; buyers chosen on recent deals or stated criteria is 1; a call timed to the week a buyer shows it is acquiring is 2.
Its own channel to buyers: nothing published is 0; insights or a newsletter with no stated audience is 1; a newsletter or podcast with a stated audience of financial decision makers is 2.
Deals closed, in figures: no named transaction is 0; named transactions, or a total or a count but not both, is 1; a total value and a count of its advisory transactions is 2. A total that covers capital raising alone earns 1.
7 columns. Drag the table sideways; the first column stays put.
Firm
Buyer list
Buyer data
Live timing
Own channel
Deals, in figures
Total
spectup
2
2
2
2
2
10
Baird
1
2
1
1
2
7
William Blair
1
1
1
1
2
6
Capstone Partners
1
1
1
1
1
5
Houlihan Lokey
1
1
1
1
1
5
Harris Williams
1
1
0
1
1
4
Hyde Park Capital
1
0
0
1
2
4
PMCF
1
1
0
1
1
4
Stout
1
1
0
1
1
4
Clearsight Advisors
0
0
0
1
2
3
Lincoln International
1
0
0
1
1
3
Oaklins
1
0
0
1
1
3
Livingstone Partners
0
0
0
1
1
2
spectup is the only firm that scores two on buyer list and on live timing; four others score one on timing.
Figure 03Bank-owned and listed firms score no better than the other six on any checkShare of the points available on each check, %, for the six firms owned by a bank or an accounting group or listed on a stock exchange, and for the other six firms without spectup: Baird, Hyde Park Capital, Livingstone Partners, Oaklins, Stout and William Blair, from each firm's own pages, 2 Nov 2026
Figure 03 data: Bank-owned and listed firms score no better than the other six on any check
Scenario
Owned by a bank, an accounting group or the stock market (6)
Independent firms, a network and two that state no owner (6)
Gap
Buyer list
42%
42%
0%
Buyer data
33%
33%
0%
Live timing
17%
17%
0%
Own channel
50%
50%
0%
Deals in figures
58%
75%
17%
Each firm's own website, checked 2 Nov 2026
When two firms tie on points, the higher review score on Clutch or Trustpilot with five or more reviews decides. On 2 Nov 2026 none of the tied firms had five reviews on the profiles read, so ties stay alphabetical.
Capstone Partners and Houlihan Lokey share five points; Harris Williams, Hyde Park Capital, PMCF and Stout share four; Clearsight Advisors, Lincoln International and Oaklins share three. Baird, William Blair and Livingstone Partners each have a total no other firm shares.
The scores measure what a firm shows on its own pages. A firm that publishes little can still be among the best M&A advisory firms for your sale or purchase, so use the scores to decide whom to ask for proof.
Three names often listed with M&A advisory firms are left out: BD Emerson, which sells diligence and integration work and names no advised transaction; MarshBerry, which its own page says Lincoln International has acquired and whose M&A pages speak to insurance, wealth and accounting firms; and Morrissey Goodale, whose M&A pages could not be read for this edition.
1. spectup: a buyer list built per transaction and approved by the owner
spectup is a private capital advisory firm that advises on buy-side and sell-side M&A and raises capital for companies and funds. It works one side of a transaction and brings the other to the table: for a sale it acts for the seller and is paid by the seller, and for a purchase it acts for the acquirer only.
Figure 04spectup in three figures
$150M+Advised on M&A
150+Transactions since 2022, capital raising and M&A together
2,000B2B financial decision makers on the newsletter
spectup.com/ma-advisory and spectup.com/sell-side-advisory, 2 Nov 2026
On a sale it builds the acquirer list for each transaction, across strategics and funds, and the owner approves every name before anyone is contacted.
It checks the list against data from its own closed transactions, what each acquirer has bought and at what size, and its in-house signal engine flags the week an acquirer becomes a buyer. On a purchase it researches each owner and calls when something opens the door to a sale.
It reaches 2,000 B2B financial decision makers through its own newsletter and runs a podcast with 8,000 listeners. The $150M+ counts M&A only; the 150+ transactions since 2022 cover capital raising and M&A together.
2. Baird, an employee-owned bank with a sponsor database
Baird is the investment banking division of a broker-dealer founded in 1919 and headquartered in Milwaukee. The firm calls itself privately held and employee-owned, with industry bankers covering more than 50 sectors.
Its Financial Sponsors Group says it keeps a proprietary database of its sponsor network, built from its own meetings and processes. Its transactions page counts 1.1K+ transactions and $546B+ of deal value since 2021, for M&A and capital markets together.
Its sponsor group says it understands each sponsor's current fund status, yet nothing on its pages says an approach is timed to it, which holds timing at one point.
Ten of the twelve other firms describe a buyer group they already hold, and none says the owner approves the list.
3. William Blair, an independent partnership with a printed M&A record
William Blair is an independent, employee-owned partnership founded in 1935 and based in Chicago. Its M&A pages list sell-side, divestiture and acquisition advice, and its investment banking group publishes insights and a podcast, with no audience stated.
It counts over 310 sales to financial sponsors in five years and says they give it proprietary insight into each sponsor's criteria and behaviour. Its M&A page prints over 917 M&A transactions and approximately $576 billion in value since September 2021, which includes large and public-company deals.
Its record earns the full two points, a total and a count printed together; its data and timing rest on what it says it knows about sponsors.
4. Capstone Partners, a middle-market bank owned by a bank
Capstone Partners is a middle-market investment bank headquartered in Boston, with 14 offices in the US and bankers who each specialise by industry and sector. Its broker-dealer is a subsidiary of Huntington Bancshares, and its contact page invites owners with EBITDA above $10 million.
It names a network of strategic and financial acquirers, and its sponsor team says it captures proprietary data on each private equity firm's criteria and buying patterns. Its homepage counts 750+ deals completed; the $20 billion on its placements page is capital raised.
It counts deals but not the value advised, so its record earns one of two points, and each of its other four checks earns one.
Only four of the thirteen describe a fee structure: spectup, Capstone Partners, Houlihan Lokey and Hyde Park Capital.
5. Houlihan Lokey, a listed bank with a ranked M&A count
Houlihan Lokey is a global independent investment bank listed on the NYSE as HLI, founded in 1972 and headquartered in Los Angeles, with M&A in its Corporate Finance segment. Its annual report counts more than 1,900 financial professionals and says a majority of Corporate Finance engagements are mid-cap.
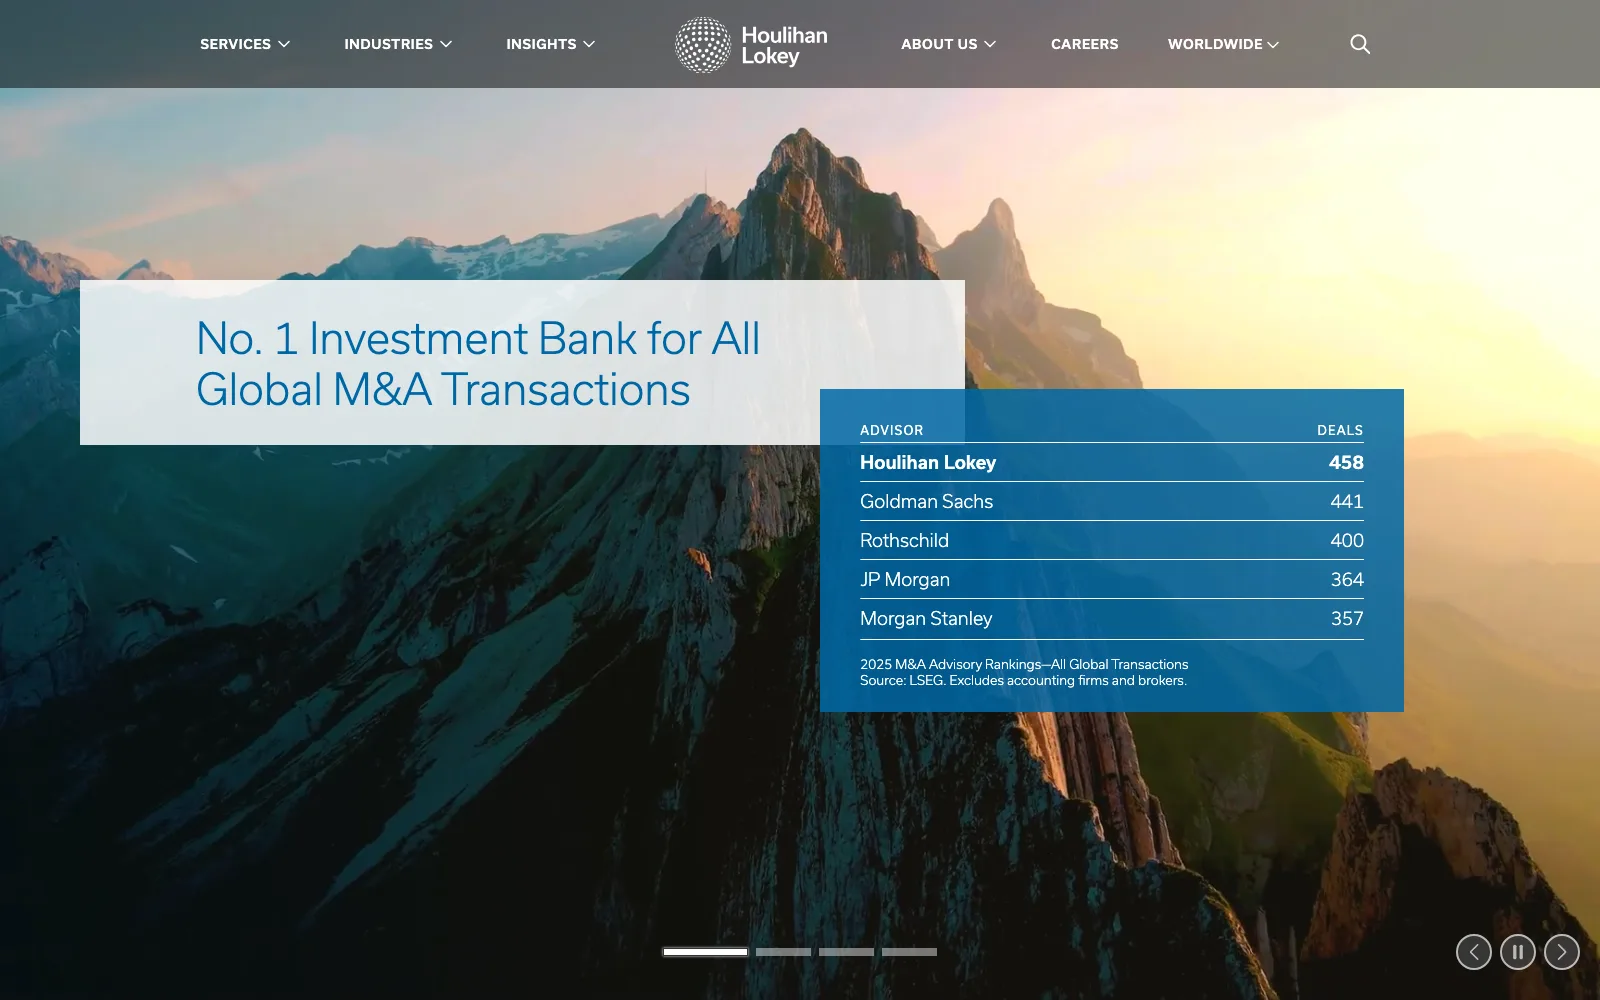
Its M&A page says LSEG ranked it first for all global M&A transactions in 2025, with 458 deals, ahead of Goldman Sachs with 441 and Rothschild with 400 in its table of top M&A advisory firms. It names closed deals with the side it advised. Its financial sponsors page counts about 2,000+ relationships and says it holds extensive information on their buying behaviour.
It prints no total value of M&A advised and describes no database or live signal behind that behaviour, so it scores one point on each check.
Houlihan Lokey says it closed more than 450 M&A transactions in a year, the largest yearly count any firm on this page prints.
Figure 055 of the 13 firms print both a total value and a count of their transactionsOne square per firm on this page, by the record it prints on its own pages. Total value and count: spectup, Baird, William Blair, Hyde Park Capital and Clearsight Advisors. A count only: Capstone Partners, Houlihan Lokey, Oaklins and Livingstone Partners. Named deals only: Harris Williams, PMCF, Stout and Lincoln International.
Figure 05 data: 5 of the 13 firms print both a total value and a count of their transactions
Group
Count
Of
A total value and a count of transactions
5
13
A count, no total value
4
13
Named deals only
4
13
Each firm's own website, checked 2 Nov 2026
6. Harris Williams, a global bank organised in eight industry groups
Harris Williams is a global investment bank for M&A and private capital advice and, like Capstone Partners, owned by a bank, with eight industry groups and clients in over 30 countries. FINRA BrokerCheck lists it as a subsidiary of PNC Bank, and its London entity is regulated by the Financial Conduct Authority.
It says it has worked with hundreds of global private equity groups and monitors thousands of buyer discussions each year. Its client pages name deals, such as Trinity Consultants acquired by Veritas Capital, and print no amount and no side.
Nothing on its pages ties an approach to a buyer's criteria or signals, which leaves timing at zero.
7. Hyde Park Capital, a boutique with a stated size band
Hyde Park Capital is a boutique middle-market investment bank founded in 2000, headquartered in Tampa with offices in Nashville, San Francisco and West Palm Beach. Its FAQ says it generally executes M&A transactions from about $20 million to $500 million+ of enterprise value.
Fees are primarily success-based on closing with a modest retainer, with no percentages. It counts more than 300 M&A transactions and over $11 billion in enterprise value since 2000.
That record is its strongest check; its pages describe no buyer data and no timing from buyer signals.
Only two of the thirteen print a transaction value band in figures: Hyde Park Capital and Livingstone Partners.
8. PMCF, the bank affiliated with an accounting firm
PMCF is the investment banking affiliate of Plante Moran, an accounting and consulting firm, the only one of these M&A advisory firms attached to an accounting practice, with offices in Chicago, Detroit, Denver and Grand Rapids and 27 international cities through Corporate Finance International.
Its sell-side page names industry-focused strategic and private equity buyers, and its buy-side page cites proprietary research tools without saying what they hold. It names closed deals, such as the sale of Metal Center, Inc. in October 2026, with no amounts and no total.
Those two gaps, the tools with no stated contents and the deals with no amounts, hold buyer data and its record at one point each.
9. Stout, valuation and disputes next to M&A
Stout is a global advisory firm in valuation, disputes and transactions, founded in 1991 and headquartered in Chicago, with its investment banking group established in 1997. It advises family-owned businesses, private equity portfolio companies and divisions of large corporates on sales.
It says it identifies likely strategic and financial buyers for each situation using its resources and databases, with no source or contents given. It has completed transactions in more than 80 countries.
It prints no total value and no count of transactions, and says nothing about what its databases hold, so its data and its record each earn one point.
All thirteen firms publish under their own name; only spectup states how many financial decision makers read what it publishes.
10. Clearsight Advisors, the specialist in business services and technology-enabled services
Clearsight Advisors is an investment bank focused on business services and technology-enabled services, founded in 2011 and headquartered in McLean, Virginia. It is a wholly owned subsidiary of Regions Financial Corporation.
It calls its relationships unmatched, with no number, no buyer group and no per-deal list described. Its CEO letter counts more than 170 transactions totaling over $20B since its founding, while its 2026 summary PDF says 165+ deals.
Nothing on its M&A pages says how it finds a buyer, so its points rest on its record and its sector monitors.
11. Lincoln International, a listed bank for the private capital markets
Lincoln International is a global advisory firm focused on the private capital markets and, with Houlihan Lokey, one of the two M&A advisory firms here that trade on the NYSE, as LCLN, headquartered in Chicago, with more than 1,400 professionals in more than 30 offices in 14 countries.
It names its private equity relationships as a buyer group; the proprietary database it cites feeds its private market valuations index, and no record of what buyers have bought is described. It counts 3,800+ conference attendees in 2025 and prints no total value and no count of transactions.
Buyer data and timing score nothing; the rest comes from a named buyer group, its newsletters and its named deals.
12. Oaklins, a network of independent member firms
Oaklins is the only network among these M&A advisory firms: a global group of independent mid-market M&A and corporate finance firms under one brand. Its member firms advise clients, each separately regulated where it operates, with advisory teams in 40 countries and 900+ advisors.
It names the buyer groups it reaches, strategic acquirors, financial sponsors and cross-border buyers, and attributes its buyer knowledge to local teams. By its own count it closed 1,900 deals in the past five years, without a total value.
Buyer data and timing score zero at group level, because the group pages leave both to the member firms.
Four of the twelve other firms print both a total value and a count of their advisory transactions: Baird, William Blair, Hyde Park Capital and Clearsight Advisors.
13. Livingstone Partners, the cross-border mid-market partnership
Livingstone Partners is an independent, global, mid-market investment bank providing M&A and debt advisory, with more than 155 professionals in 15 offices in Europe, the United States and Asia.
It says it completes more than 85 transactions a year, valued between €25 million and €500 million, with about three in five crossing borders. Its global reach page cites long-standing relationships across North America, Europe and Asia, with no number, no database and no approval step stated.
Its insights section and its count of transactions are where it scores.
How spectup finds buyers and times the call
spectup is the one firm here that states the owner approves every name on the acquirer list before anyone is contacted, and on a sale it writes that list for each transaction. spectup checks it against data from its own closed transactions, what each acquirer has bought and at what size, and its in-house signal engine watches for the week an acquirer becomes a buyer.
On a purchase it researches each owner and calls when something opens the door to a sale, such as succession, a funding gap or a competitor selling.
Sales and purchases run on the same reach: a newsletter to 2,000 B2B financial decision makers, a podcast with 8,000 listeners and a million impressions a year in front of this market, so many owners already know spectup when it calls.
How spectup runs a sale or a purchase
spectup acts on one side of the transaction. On a sale it releases the company to buyers in three steps: nothing signed, after the NDA, and after an offer. It names the owner to an acquirer only against a signed and dated agreement, and it records, for every party, what it received and on what day.
Figure 06At spectup, a buy-side search approaches owners from week 5; the first five weeks build and agree the shortlistspectup's buy-side search by stage, in weeks from the start of the work, as spectup.com/buy-side-advisory states them. Fading: runs until the work is done. Diligence starts once an owner engages and signing once terms are agreed, so neither has a week; there is no fixed term.
Figure 06 data: At spectup, a buy-side search approaches owners from week 5; the first five weeks build and agree the shortlist
Track
What
When
Thesis
1 to 2 week
Universe
2 to 4 week
Shortlist
3 to 6 week
Approach
5 to 8 week
Retainer
1 to 8 week
spectup.com/buy-side-advisory, how a buy-side search runs, 2 Nov 2026
On a purchase the owner states the acquisition criteria in writing and spectup builds the longlist against them, with a rationale for each company. It screens, ranks and agrees the shortlist with the owner, approaches the owners directly, in the buyer's name or on a no-names basis, and manages the process through diligence to signing.
The fee has two parts: a retainer paid each month the work runs, and one transaction fee, capped, when the deal closes, and the first call ends with both figures in writing.
What should you ask an M&A advisory firm before you sign?
Before you sign with any firm above, ask it:
Which sales or purchases of our size and sector have you closed in the last two years, and are they named on your site, with amounts?
How do you find the buyers: a list built for our transaction that we approve, or a standing roster of relationships?
What do you know about each buyer: what it has bought, at what size, and from which of your own transactions?
When do you call a buyer: on a schedule, on its stated criteria, or in the week it shows it is acquiring?
What do you publish under your own name, and how many financial decision makers does it reach?
Do you act for the seller, for the buyer, or for both sides of any transaction?
How are you paid: retainer, success fee, incentive fee, and is the transaction fee capped?
Which of the thirteen M&A advisory firms fits your company?
2 columns. Drag the table sideways; the first column stays put.
If you are
Look first at
Selling and want to approve every buyer name before anyone is called
spectup
Buying and want a longlist built to written criteria, with owners approached directly
spectup
A US middle-market owner who wants a bank with a large sector bench
Baird, Capstone Partners, Harris Williams, William Blair
In business services or technology-enabled services
Clearsight Advisors
Selling across borders in Europe, the US and Asia
Livingstone Partners, Oaklins, Houlihan Lokey, Lincoln International
A company that wants a listed bank
Houlihan Lokey, Lincoln International
Looking for a bank next to an accounting firm
PMCF
Looking for valuation and disputes work under the same name
Stout
A company of about $20 million to $500 million of enterprise value, with success-based fees
Hyde Park Capital
Mergers and acquisitions advisory firms split on two questions: who finds the buyers, and when they are called.
Houlihan Lokey and Lincoln International are the two listed banks here, and both place themselves in the mid-market: Houlihan Lokey says a majority of its engagements are mid-cap, and Lincoln calls itself a top global M&A advisor to the mid-market.
If you want the list built for your transaction, every name approved by you and the call timed to the week a buyer is acting, put the questions above to spectup.
Where you are19 sections
/ 07
What clients say about our capital advisory
"The outreach generated 44 investor meetings and saved me countless hours of unqualified calls."
Jonathan WeinsFounder & CEOPopMealsFood technology
6 questions on M&A advisory firms, answered by Edwin Mik, Partner & Head of IR.
01What fees do M&A advisory firms charge?
Four of the thirteen M&A advisory firms describe how they are paid. spectup charges a retainer for each month of work and one transaction fee when the deal closes. Capstone Partners describes a retainer, a success fee and an incentive fee as typical, and Houlihan Lokey names retainer, progress and completion fees in its annual report. Hyde Park Capital says its fees are primarily success-based on closing, with a modest retainer. None of the four publishes rates, so ask the other nine for theirs in writing.
02What size of company do M&A advisory firms take?
Few say. Hyde Park Capital says it generally executes M&A transactions from about $20 million to $500 million+ of enterprise value, and Livingstone Partners puts its transactions between €25 million and €500 million. Capstone Partners invites owners with EBITDA above $10 million. The others publish no range.
03Does an M&A advisory firm work for the buyer and the seller?
In one transaction, an advisor acts for one side. spectup acts on one side only, and you can ask any firm to confirm its side in writing.
04How do M&A advisory firms find buyers?
Most name a buyer group they already hold, each measured differently. Baird counts 79,000+ connections in its sponsor network, William Blair counts over 310 sales to financial sponsors in five years, and Harris Williams says it has worked with hundreds of global private equity groups. spectup builds the acquirer list for each transaction and the owner approves every name before anyone is contacted.
05How long does selling or buying a company with an advisor take?
spectup's M&A page puts a transaction at six to twelve months from scope to signing, and none of the other twelve publishes a standard length. It says a buy-side search has no fixed term, because it depends on when an owner on the list wants to talk. It builds and screens the longlist in the first weeks and starts approaching owners from week 5, once the owner has agreed the shortlist. So a purchase reaches its first owner conversations about a month in, while the close itself depends on that owner. Ask each firm for the dates of its last three closings and for the longest gap between signing and closing.
06Why are there no Big Four firms on this list?
This edition ranks investment banks and advisory firms that run M&A under their own name and show their record on their own pages, because each of the five checks is read from those pages. The Big Four sell corporate finance through accounting and consulting groups and were not scored. A firm that publishes how it builds its buyer list, its data, its timing, its channel and its deals can be added to the next edition.