Mandate size
- Does the firm take low and mid-market placements, or does the mandate floor start at institutional fund size?
 Request Call
The 6 best private placement agencies in 2026, ranked on mandate scale, investor coverage and fees. Five global franchises, one low and mid-market desk.
spectup is one row of six. The case against it is in the profile below, in the same format as the other five.
6 columns. Drag the table sideways; the first column stays put.
| Firm | Rating | Best for | Pricing | Track record | Approach |
|---|---|---|---|---|---|
| 01spectup | 4.9/5 | Low and mid-market placements for funds, companies and listed issuers | Monthly retainer + placement fee on capital that closes | $760M+ placed and advised across 150+ mandates since 2022 | Capital strategy, valuation, offering materials, named investor list, outreach and close |
| 02PJT Park Hill | Institutional tier | Established fund GPs raising institutional LP commitments above $500M | Institutional success-fee placement-agent model | Top-tier global placement franchise with Blackstone and PJT lineage | Deep LP coverage across PE, private credit, real estate, infrastructure, and secondaries |
| 03Lazard Private Capital Advisory | Tier-one | Fund GPs running primary raises, secondaries, or continuation vehicles | Negotiated success fees sized to transaction value | Global investment-bank private capital advisory franchise | Strong secondaries, cross-border LP coverage, and structured capital advice |
| 04Campbell Lutyens | Specialist | Independent PE, credit, real assets, and infrastructure fund placements | Institutional placement mandate economics | Independent specialist operating since 1988 | Independent advisor positioning with senior LP outreach coverage |
| 05Eaton Partners | Established | Alternative investment managers seeking Stifel-backed distribution | Success fee on closed commitments, sometimes with retainer support | Alternatives placement franchise operating since 1983 | LP database across pensions, endowments, sovereign wealth, and insurance balance sheets |
| 06Piper Sandler Private Capital | Bank platform | Mid-market private capital placements through an investment-bank platform | Bank-led private capital placement economics | Private capital team inside Piper Sandler’s broader banking platform | Useful for mid-market equity placements and adjacent banking relationships |
The axes, and the test each one applies. Every firm below was read against the same five.
Brand recognition is the easiest thing to compare and the least decisive. What decides it is the size of mandate the firm takes, the investor book it places into, and how much senior time each mandate gets.
spectupLow and mid-market placements for funds, private companies and listed issuers
Best fit when the mandate is a low or mid-market placement and the issuer wants the same partners on it from structuring through to close.
Institutional fund placements above $500M
A top institutional placement agent, but usually the wrong product for an operating company.
Secondaries, continuation vehicles, and institutional private capital advisory
Excellent for institutional private capital work; not a company-side fundraising consultant.
Independent fund placement and secondaries advisory
Best for managers that value independent placement advice at institutional scale.
Alternative fund managers seeking Stifel-backed distribution
A credible alternatives placement franchise for fund managers, not most companies.
Mid-market private capital placements within a banking platform
A bank-platform option when the transaction is already institutional enough to warrant it.
A private placement agency is mandated by an issuer to raise capital from institutional and private investors without a public offering: it structures the raise, prepares the offering materials, works a named investor list to a timetable, and sits in the process through to close.
Every firm on this page places capital privately. What separates them is the size of mandate each one is built to run.
Institutional franchises price a percentage of committed capital calibrated to $250M+ fund closings, which is where their mandate floors sit. A low or mid-market placement needs a desk priced for that size instead.
The six agents ranked here split by the mandate each one is built for:
Match the mandate before you compare the brands. A $1B fund close and a low or mid-market placement need different investor coverage, different economics, and a different amount of senior time per mandate.
Three client stories below show what happens when the mandate and the agent are mismatched, and what a buyer sees once the mandate is defined.
A reader searching for the best private placement agency gets six firms that all place capital privately and are built for very different mandates. Five are institutional franchises whose default engagement is a fund close at institutional scale. One is spectup, the low and mid-market desk. The SERP ranks them together and says nothing about the mandate each one takes, so the axes below do.
I'm Niclas Schlopsna, managing partner at spectup, a Munich-based private capital advisory firm founded in 2022. We act as private placement agent for funds, private companies and listed issuers, and we have raised, placed and advised $760M+ across 150+ mandates since 2022. At least once a quarter an issuer lands on our calendar after weeks with a franchise whose mandate floor was always going to turn the raise down.
A private placement agency places securities privately for the issuer that mandates it: a fund manager raising a vehicle, a private company raising growth equity or private debt, or a listed issuer running a PIPE. What it never runs is a public offering. The capital comes from:
The perimeter is public record. Investopedia's primer on placement agents describes the intermediary role between issuers and institutional investors. FINRA's private placements page covers the regulatory perimeter that broker-dealers operate inside. SEC Regulation D guidance spells out the exempt-offering rules a private placement runs under. What none of them settle is which agent fits which mandate.
The firms that answer this query are not interchangeable. A global franchise carries a mandate floor, an institutional LP book and senior coverage of the largest pensions and sovereigns, and its fee only funds that infrastructure above a certain size. A dedicated low and mid-market desk carries a smaller book it owns outright, takes few mandates at a time, and keeps the same partners on each one from structuring to close. Both are placement agents. The mandate decides which one clears.
This comparison ranks six private placement agents, names what each one is built for, and tells three stories about what happens when the mandate and the agent do not match. The right agent depends on what you are placing, from whom you are raising it, and at what size.
Five axes separate the six agents on this page. Every one of them places capital privately, so the axes measure the mandate each firm is built to run rather than the category it belongs to.
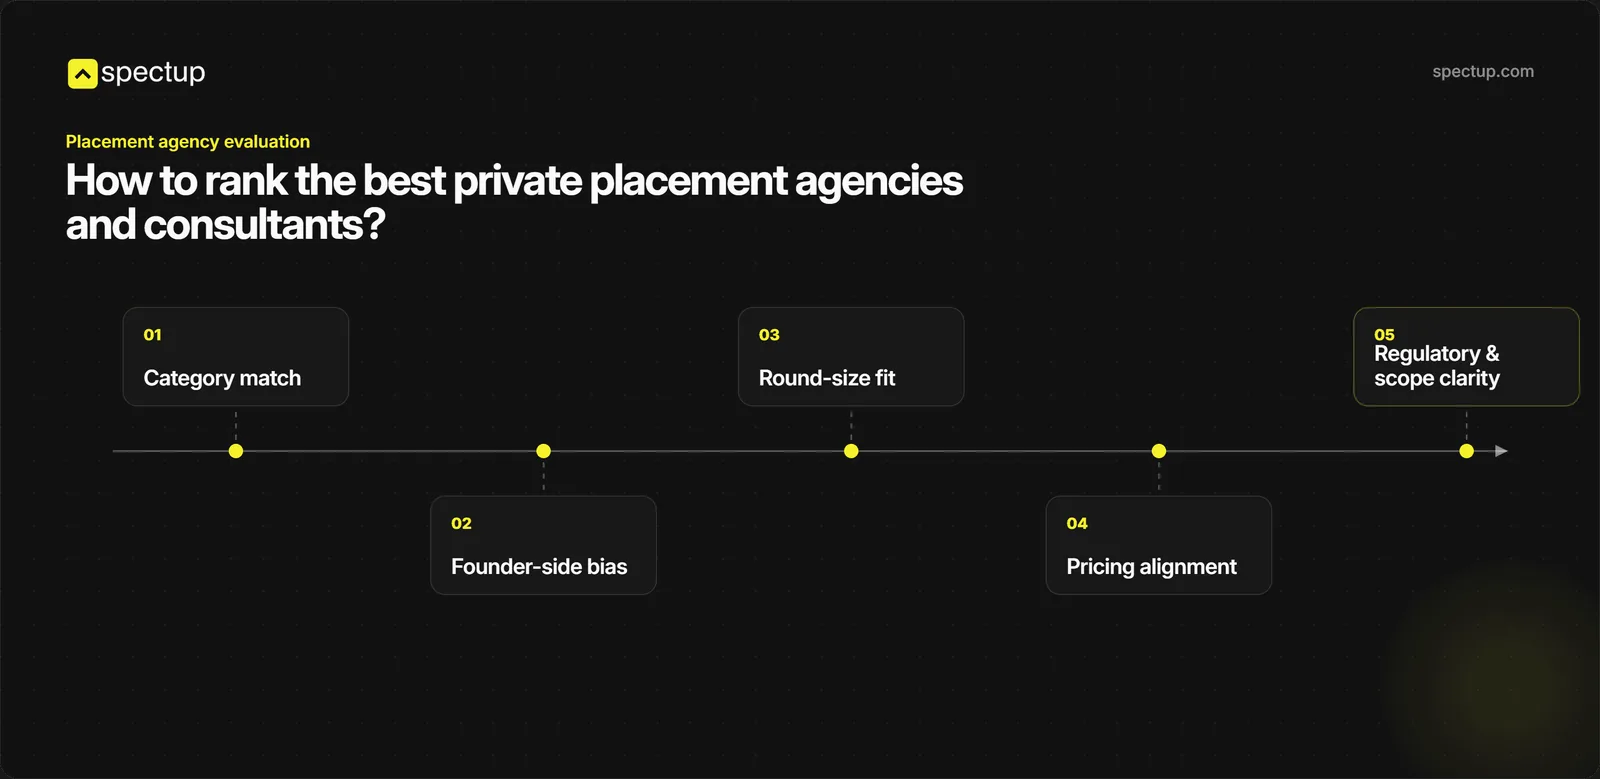
An institutional franchise and a low and mid-market desk are both private placement agents. What separates them is the mandate: the size it has to clear, the investor book it lands in, and who is still on it in month ten.
Each firm's public materials, FINRA BrokerCheck record, and disclosed mandate profile were reviewed end to end. Aggregate "billions in capital raised since founding" figures were treated as platform context across multi-decade firm history, not per-mandate evidence of fit for any specific raise. NVCA research on private capital deal flow is a useful cross-reference on how much capital actually moves at the lower end of the market.
spectup acts as private placement agent for funds, private companies and listed issuers, raising institutional and private capital without a public offering. The mandates are low and mid-market, where a dedicated desk is the difference. Sectors:
Mandated out of Munich and executing across four regions: North America, Europe, the Middle East and Asia Pacific. A placement runs wherever the capital for that strategy sits, which is rarely the market the issuer is in.
Mandate types. Three issuer types, one engagement model. spectup is mandated by one side of a transaction and paid by that side only.
On every mandate the single deliverable is capital that closes: signed subscription documents rather than a list of introductions.
Five workstreams run under one mandate: capital strategy, valuation and positioning, offering materials (PPM, investor deck, financial model, term sheet, data room), investor targeting and outreach, and diligence through close. Our private placement agent service page details the full scope and what the issuer holds at the end of each workstream.
Which side we represent:
One side per transaction, by design. spectup has no proprietary products, no fund affiliations and no distribution agreements, and on any single transaction it is mandated by one side and paid by that side only. Five of the six firms in this comparison structurally represent the fund manager raising from LPs. spectup takes the mandate from the fund, the private company or the listed issuer, and brings the investors to the table.
Mandate size:
Low and mid-market, where a dedicated desk is the difference. The limit is size and fit rather than licence. A pre-revenue, pre-product company and a raise with no defined use of proceeds are both outside what we take on, and the largest institutional fund closes belong with a global franchise: five of them are on this page.
£100M is the largest single round we have placed on one mandate. The desk is built for the low and mid-market placements under it.
Pricing alignment:
A monthly retainer plus a placement fee on capital that closes, both written into the mandate before the first investor is approached. Ten monthly retainers run over a typical mandate term, then the fee. There is no rate card: both are set against the instrument, the size and the jurisdictions.
We don't take pure-success-fee work because alignment requires both sides to commit, and we don't bill hourly because hourly billing rewards drag rather than closure. Compare that with the placement-agent model:
Regulatory and scope clarity:
spectup is not a US registered broker-dealer. US-related activity is conducted under SEC Rule 15a-6 through a chaperoning arrangement with a U.S. registered broker-dealer that is a FINRA and SIPC member. Mandates are run out of Munich across four regions, and that arrangement is what covers the US leg of a cross-border placement.
Track record:
Closed mandates include CreatorIQ, a $40M Series D, and PopMeals, where a single outreach campaign generated 44 investor meetings. The highest count on one mandate is 74 investor meetings, on Artly AI.
The investor book carries 440+ direct investor and LP relationships, every one out of a closed transaction, with 40+ in the inner circle the partners meet regularly. Against it run 80+ triggers watched continuously for the week capital becomes allocatable, and Valicon.ai on what each name has written before. Other advisors license a database; spectup built both halves, so the coverage and the timing come from the same place.
Where the trade-offs are real:
Active mandate count is intentionally capped to preserve senior delivery, and the slate is sometimes wait-listed.
Park Hill Group is one of the most established institutional placement franchises in private markets. Originally a unit of Blackstone, it spun out as part of PJT Partners in 2015 and continues to operate as:
Private Equity International's placement agent rankings consistently put PJT Park Hill in the global top tier.
Typical mandate sizes start at $500M and run into the multi-billion range, with senior partners covering the largest pensions, sovereigns, and endowment LPs. Sector teams cover PE, private credit, real estate, and infra with dedicated specialists. The mandate selection skews to established managers raising successor funds where prior-vintage track record can carry the pitch.
Where it fits?
Established fund GPs raising institutional LP commitments above $500M who want top-tier LP coverage and a brand that institutional investors recognize from prior raises. PJT Park Hill is among the best private placement agency options in the institutional segment, full stop.
Where the gap is honest?
Park Hill does not run venture-stage operating-company raises. The mandate floor and economics make that structurally impossible. A company raising a $5M Series A from VCs is not the client profile.
Lazard's Private Capital Advisory practice is one of the dominant franchises on GP-led secondaries and continuation-vehicle transactions. The firm dates to 1848 and runs a global advisory business with deep institutional LP coverage. Crunchbase News coverage of the secondaries market documents how rapidly this corner of private capital has scaled, and Lazard sits near the top of every league table that matters
Typical engagements include primary fund placements for:
Pricing is negotiated on a success-fee basis sized to the transaction value.
Where it fits:
Fund GPs running primary raises, secondaries transactions, or GP-led continuation vehicles at institutional scale. The team is tier-one on cross-border LP coverage, and the firm's broader investment-bank reach into M&A and restructuring sometimes opens adjacent opportunities for the same client.
Where the gap is honest:
The primary deliverable is an institutional LP commitment, not a venture round. A company whose bottleneck is converting VC introductions into a wired $4M seed is not the target client.
Campbell Lutyens has been an independent placement and secondaries advisor since 1988, with offices in London, New York, Hong Kong, Chicago, Los Angeles, Charlotte, Munich, and Paris. The independence pitch matters in this corner of the market because bank-owned placement arms sometimes face channel conflicts when a parent investment bank has competing capital-markets relationships with the same LP universe.
The firm covers primary fund placements across:
Mandate selection skews to mid-market and upper-mid-market GPs where Campbell Lutyens can run the full LP outreach with senior partners in the room throughout.
Where it fits?
Independent PE, credit, and infra GPs running global institutional fund placements where independent advisor alignment is a feature, not a footnote. The firm's London headquarters and EMEA LP coverage are particular strengths for European managers, and PitchBook's private equity fundraising coverage documents how the independent placement-advisor segment has held share against bank-owned arms over the last five years.
Where the gap is honest?
Mandate floor is institutional fund-size, not venture round-size. The engagement is GP-side, not company-side at the operating-company level.
Eaton Partners has been placing alternative investment funds since 1983 and is now a division of Stifel Financial. The firm covers:
Eaton's parent Stifel provides balance-sheet support and a US middle-market investment-bank network, which extends the firm's reach into adjacent capital-markets and M&A relationships. Pricing is typically a success fee on closed commitments, with a retainer in some mandates to cover senior staffing during long fundraising cycles. SIFMA research tracks the broker-dealer underwriting and placement segment in aggregate, which is a useful sense-check on relative scale across the named firms.
Where it fits?
Alternative-investment fund GPs placing PE, credit, real assets, or hedge fund vehicles who want broad alternatives coverage from a single firm. Eaton is regularly cited among the best placement agent options in the alternatives segment specifically.
Where the gap is honest:
Piper Sandler's Private Capital practice sits inside a US middle-market investment bank with sector coverage across healthcare, technology, financial services, and industrials. The team runs equity private placements for mid-market companies and selected fund managers, with regulatory coverage as a FINRA-registered broker-dealer under the parent firm.
Piper Sandler is also the firm that ranked third on the SERP for the broader private placement agency query in our April 2026 DataForSEO pull, which tells you something about how middle-market equity placements have grown as a distinct product line between traditional venture rounds and full-scale IPOs. HBR's coverage of corporate finance traces the same shift from a corporate-strategy lens.
Where it fits:
The investment-bank platform offers cross-product reach into M&A and capital markets within the same parent.
Where the gap is honest:
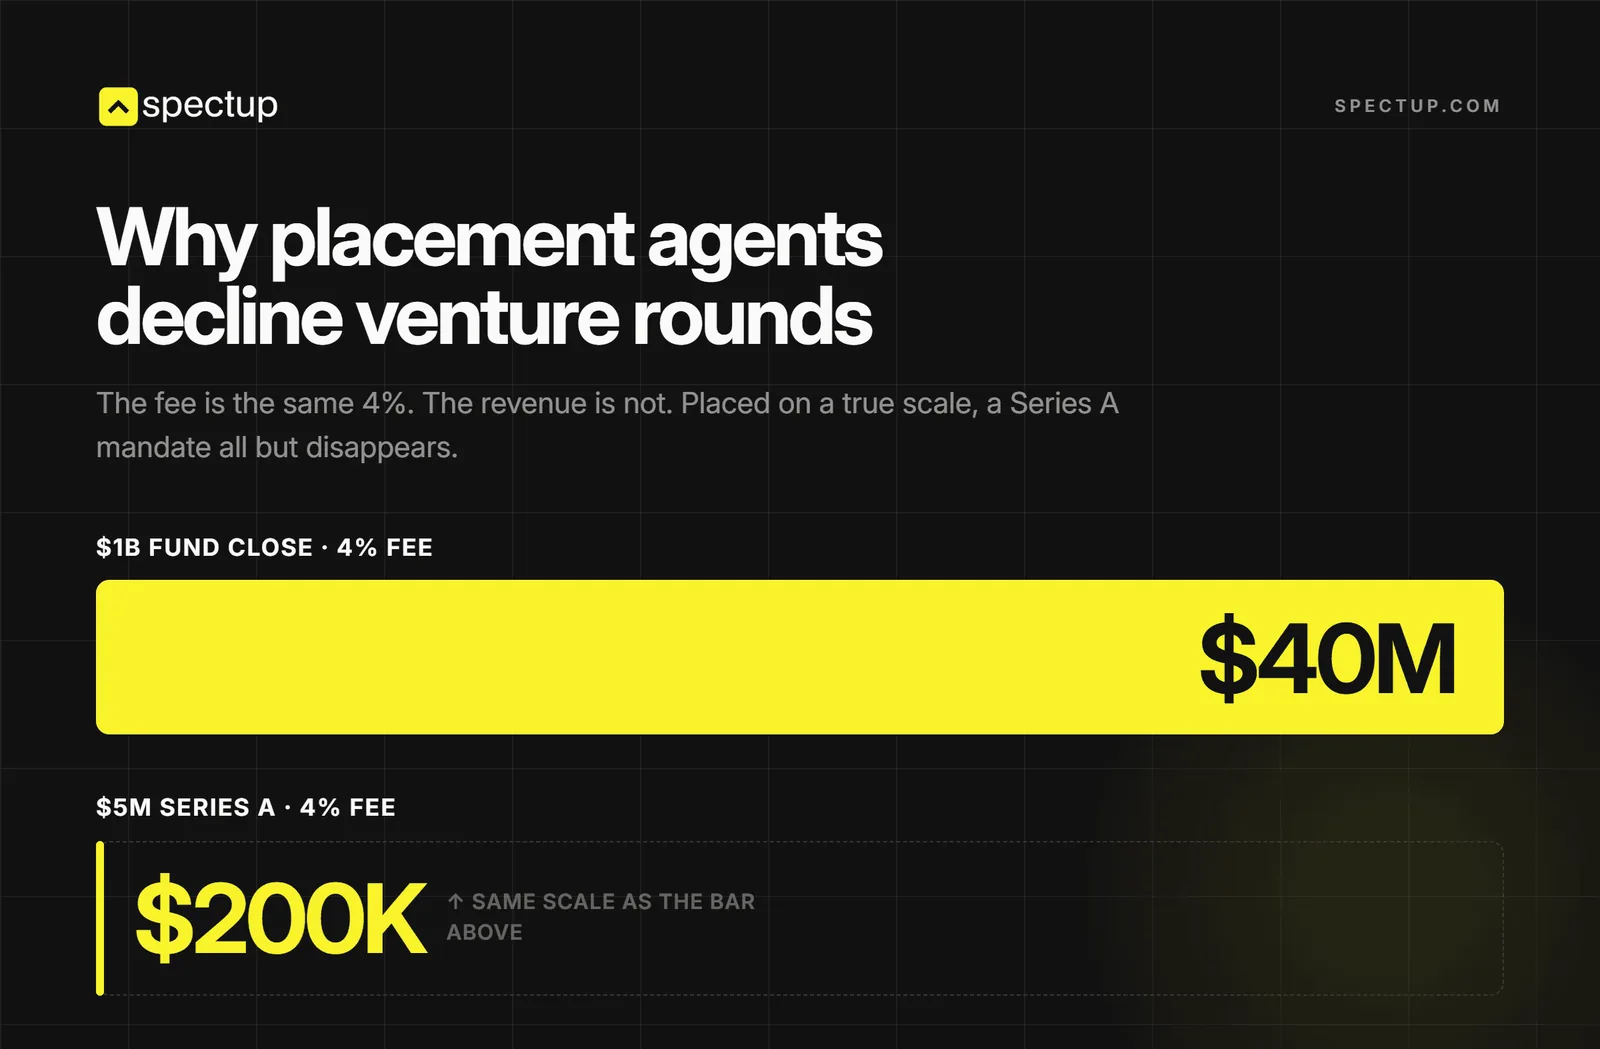
This is where mandate size pulls the models apart hardest.
A traditional placement-agent commission on a $1B fund close at 4 percent is $40M of revenue
It fully funds the institutional infrastructure the agent runs: senior partner LP coverage, dedicated sector teams, multi-year fund-marketing cycles, compliance overhead, broker-dealer reporting. The same 4 percent applied to a $5M placement is $200K, which does not pay for a quarter of that infrastructure.
That math is why a global franchise carries a mandate floor, and why a low or mid-market raise rarely gets past an intake call there. The work does not shrink with the mandate: the same structuring, offering materials, named investor list and diligence run on a $5M placement as on a $1B fund close, which is why a desk that takes the smaller mandate runs few at a time and prices a retainer against the process rather than a percentage against the close. A venture-backed company raising a round rather than placing a security is a different job again, and the spectup ranking of fundraising consultants covers that shortlist.
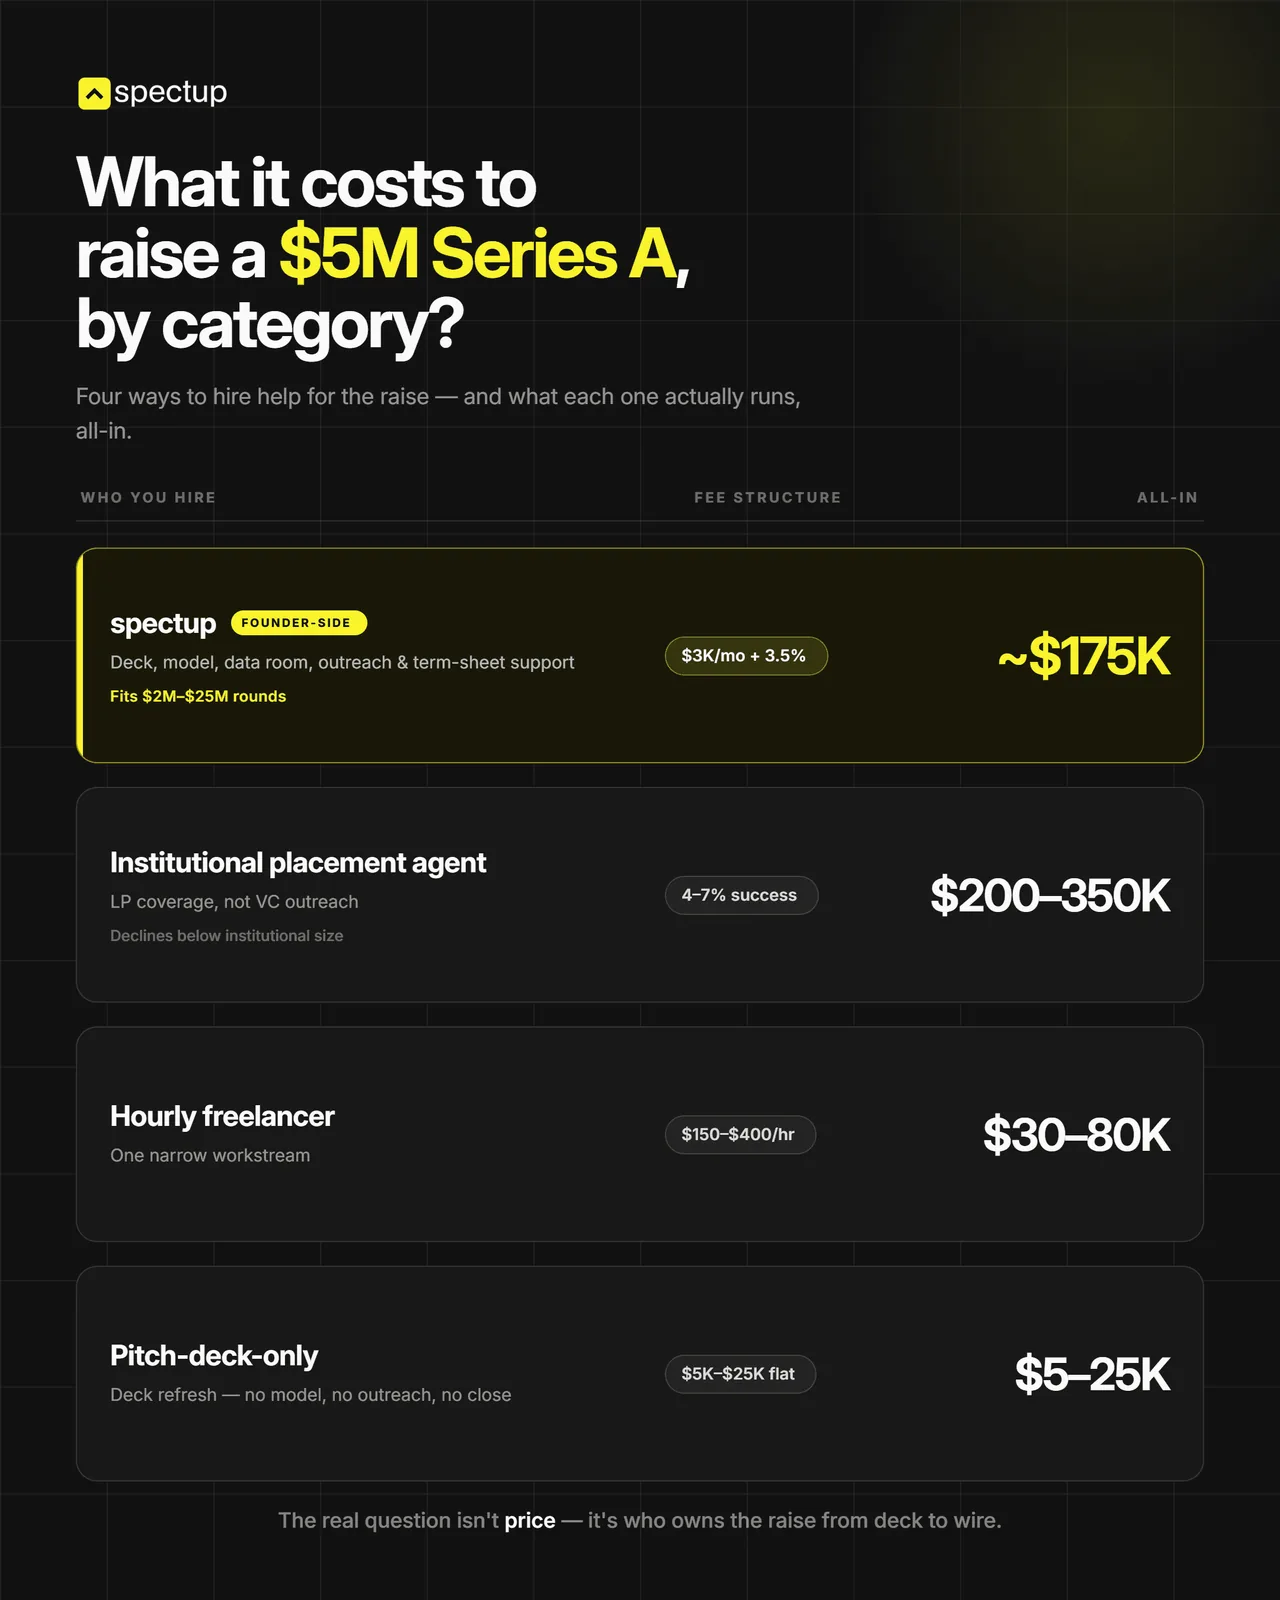
Below is the rough cost-per-outcome math across the models for a $5M raise, the low end of the market this page covers. Numbers are approximations to illustrate the structural pattern, not quotes from any specific firm.
4 columns. Drag the table sideways; the first column stays put.
| Model | Typical Cost | What You Get | Right Fit For |
|---|---|---|---|
| spectup (low and mid-market placement) | Monthly retainer plus a placement fee on capital that closes | PPM, deck, model, data room, named investor list, outreach, close | Low and mid-market placements |
| Institutional placement agent | 4 to 7% success ($200K to $350K on $5M, but firms decline below institutional size) | LP coverage for fund GPs, not VC outreach | $250M+ institutional fund placements |
| Hourly freelance consultant | $150 to $400/hr ($30K to $80K typical) | One narrow workstream (model, deck, or outreach only) | Companies with bandwidth to run the raise themselves |
| Pitch deck consultant only | $5K to $25K flat | Deck refresh, no model, no outreach, no close | Companies with strong investor relationships already |
The structural takeaway is simple. A percentage built for a $1B fund close does not fund a desk on a $5M one. If a small firm pitches a 5 percent success-fee-only deal on a low or mid-market raise, ask whether it is a registered broker-dealer (FINRA BrokerCheck is the public record) and what its last three closed mandates actually were.
The clearest way to see the difference between these firms is to watch what happens when the mandate and the agent do not match. Three stories from the last 12 months of intake calls, anonymized and lightly composited to protect specific deal terms.
Anna runs a Series B biotech out of Munich with EUR 15M of target raise on the table and roughly EUR 18M in committed funding from prior rounds. She heard the phrase placement agent at a conference, Googled best private placement agency, and ended up on the website of a mid-tier institutional placement franchise. Three weeks of email back-and-forth followed.
The placement-agent intake partner was polite. He told Anna the firm normally needs a $250M+ mandate to take on a new client, that biotech wasn't a core sector for the practice, and that even if they were interested the commission economics on EUR 15M wouldn't justify the institutional staffing they would need to put behind it. The mismatch was mandate size, and the firm's own floor said so before the first email went out.
Anna's mandate needed a named target list of European life-sciences investors, offering materials built around the science, and a desk with the capacity to work that list for the whole process. What it did not need was a franchise whose mandate floor started at more than fifteen times her raise.
She closed the round eight months later with a different partner. The lesson she came back to share is that the six weeks cost her nothing but time, and the mismatch would have shown on day one if anyone had asked the franchise one question: what is your mandate floor.
Ravi runs a US fintech raising $4M of growth capital. His prior round closed in 2024 with a generalist consultant who delivered a deck and walked away. This time he wanted a desk that stayed in the process through to close, and he started with two New York firms that described themselves as private placement consultants on LinkedIn.
The first firm turned out to be a one-person shop running a commission-only structure: 6 percent of capital raised, no retainer, no clear scope of work between intro and close. The second firm was a registered broker-dealer that runs Reg D private placements for real estate sponsors, with a $50M floor. Neither was the right shape.
Ravi landed on a spectup intake call after his prior consultant referred him over. The first 20 minutes went on mandate fit: what $4M of growth capital has to clear, which investors underwrite that instrument at that size, and why a commission-only pitch with no retainer carries no shared cost when the process stalls. spectup does not work on success fee alone for that reason.
He left without signing that day, put the same questions to the two other firms over two weeks, and came back to sign a monthly retainer plus a placement fee on capital that closes. He is mid-mandate with a Q3 close target on the $4M. The two weeks cost him nothing and settled the choice.
Sofia runs a B2B SaaS company with a $12M target raise and $1.8M of ARR running into the conversation. She had two offers on her desk by the time she reached us. The first was a small Chicago-based outfit pitching a "placement agent for companies" service at 5 percent success only, no retainer, with a vague scope memo. The second was a senior-led desk on a retainer plus a fee on capital that closes, with a named partner and a defined 12-week outreach window.
Her diligence on the first offer started with the regulatory check. The Chicago firm was not on FINRA BrokerCheck as a registered broker-dealer, which meant the 5 percent commission structure they were pitching was probably in regulatory gray territory on a US equity placement. SIFMA's guidance on securities broker registration is the canonical reference for what crosses the broker-dealer line, and a private-placement-style commission on equity does cross it.
The second offer was structurally cleaner. A monthly retainer plus a fee on capital that closes, the senior partner named in the contract, scope written out across offering materials, model, the named investor list, outreach, meeting prep and term negotiation. Pricing alignment was visible from the first paragraph.
Sofia signed the second offer, ran the mandate through a 14-week active outreach window using our investor outreach playbook, and closed the round inside the window with a tier-one lead and two strategic co-investors. The total cost-per-outcome came in below the 5 percent commission the first firm had offered, with tighter alignment and senior delivery throughout. Her takeaway, in her own words: the retainer was the part that made the rest of it real, because everyone was paid to run the process rather than to wait for the wire.
Six questions filter out the firms whose mandate does not match yours, before you spend a calendar quarter finding that out on an intake call.
The right firm will answer all six cleanly in the first call. The wrong firm will dodge two or three of them, which is the signal that the engagement will drift and that a draft engagement letter is about to arrive for a mandate the firm was never built to run. Kauffman Foundation research on company decision patterns at fundraising milestones is consistent with the pattern: buyers that settle mandate fit and structure upfront close faster and on better terms than buyers that let an intake-call pitch frame the decision for them.
We don't compete with Park Hill on a $2B PE fund close. We don't compete with Lazard on GP-led secondaries. spectup is not a US registered broker-dealer, and on any single transaction it acts for one side only. spectup's private placement desk exists for the mandates those franchises carry a floor above: a manager raising a first or second vehicle, a private company with revenue and a defined use of proceeds, a listed issuer running a PIPE.
The thesis underneath the firm is that a low or mid-market placement deserves the same discipline institutional capital advisory has run for 50 years, sized and priced for that mandate rather than for a $1B fund close. The 440+ direct investor and LP relationships, every one out of a closed transaction, the 80+ triggers watched continuously, Valicon.ai on who allocates to what, and the media engine (Deal Makers (and Fakers) podcast, Raise or Die newsletter) are the infrastructure that makes that work at this size.
A $1B fund close and a low or mid-market placement are the same job at different scale, and they are not run by the same desk. If your raise sits in the low or mid-market, start a mandate with us by getting in touch. The expensive mistake is hiring the mandate floor rather than the mandate: a franchise built for institutional closes will price, staff and prioritise a smaller raise accordingly.
If you're hiring a private placement agency in 2026, the loudest decision your peers make is the brand decision. The expensive one is the mandate decision. The two are connected because a brand is easy to compare and a mandate floor is never published, so the question that decides the outcome rarely gets asked on the first call.
The upstream question is the only one that matters. What are you placing, at what size, and which investors underwrite that instrument at that size? Answer it cleanly and the firm choice falls out of it. If you can't, find a desk that will work the answer out with you before it sells you a contract. BCG's publications on private capital infrastructure are a useful background read on how the institutional side actually works, and our comparison of pitch deck consultants covers the adjacent decision most companies run at the same time.
The team at spectup is in the lead when it comes to quality of output. They helped us shape the direction for internal funding efforts. We worked with other fundraising consultants on different ventures, but spectup’s fundraising advisory support has been by far the best choice.
$5MRaised in total
Asked on first calls about the firms named above.
A private placement agency raises capital for an issuer from institutional and private investors without a public offering: it structures the raise, prepares the offering materials, works a named investor list and runs the process to close. The fit question is size rather than category. The largest franchises carry mandate floors at institutional fund size, and a low or mid-market placement needs a desk built for that size.
Most agents are paid a fee on the capital that closes, with or without a retainer while the process runs. spectup charges a monthly retainer plus a placement fee on capital that closes and does not work on success fee alone. There is no rate card: both are set against the instrument, the size and the jurisdictions, and both are written into the mandate before any work starts.
A placement agent is mandated to place securities privately and is paid on the capital that closes: it structures the raise, prepares the offering materials, works a named investor list and sits in the process to close. A fundraising consultant advises a company on a venture equity round and is not placing a security. spectup acts as private placement agent for funds, private companies and listed issuers, and runs a separate fundraising consultant practice for venture-backed companies.
Many placement agents operate as registered broker-dealers, and the register is public: FINRA BrokerCheck lists the firm and its CRD number. spectup is not a US registered broker-dealer, and its US-related activity is conducted under SEC Rule 15a-6 through a chaperoning arrangement with a U.S. registered broker-dealer that is a FINRA and SIPC member.
It depends on the desk. A global franchise usually declines at that size, because a percentage of the capital placed does not fund the senior coverage, sector teams and compliance it runs. A dedicated low and mid-market desk takes the mandate and prices it as a monthly retainer plus a placement fee on capital that closes, so the process is paid for while it runs.